
Jan Seva Kendra vs GroMo Commission: Which Pays More?
Savings account, demat, credit card and loans, with real numbers and how to earn from both.
In a Jan Seva Kendra vs GroMo commission comparison, GroMo pays far more per customer on financial products. A savings account pays up to ₹5 on the chart we compared, against up to ₹600 on GroMo, and a credit card has no rate on that chart but pays up to ₹2,000 on GroMo. A Jan Seva Kendra still wins on daily cash services, bills, tax filing and large loans, so most counter owners earn the most by running both. For the full Jan Seva Kendra rates, see our Jan Seva Kendra commission chart.
Below is a product-by-product comparison with real numbers, a worked example for one month, and a plan to use both together. Where Jan Seva Kendra pays more, we say so plainly.
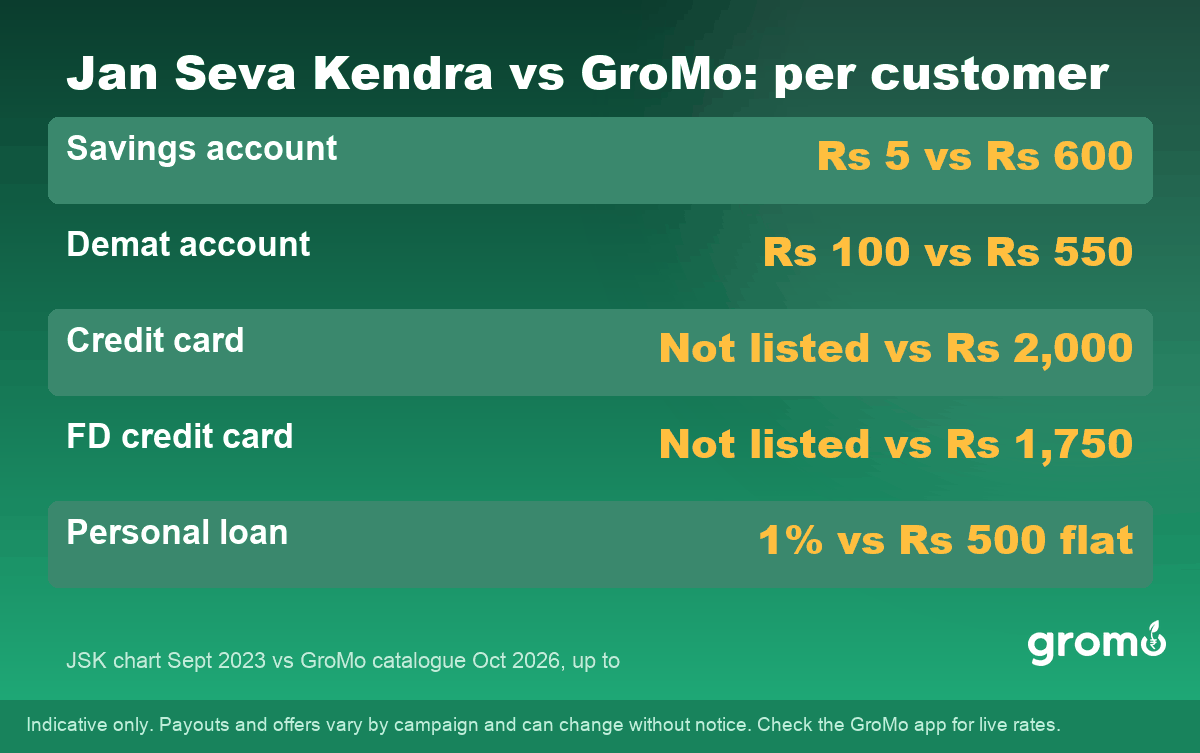
| Product | Jan Seva Kendra (chart) | GroMo (up to) | Who pays more |
|---|---|---|---|
| Savings account | Up to ₹5 | ₹600 | GroMo |
| Demat account | Up to ₹100 | ₹550 | GroMo |
| Credit card | Not listed | ₹2,000 | GroMo |
| FD-backed (secured) credit card | Not listed | ₹1,750 | GroMo |
| Investment products | Not listed | ₹1,000 | GroMo |
| EMI card / credit line | Not listed | ₹600 | GroMo |
| Personal loan | Up to 1% of loan | ₹500 flat | Depends on loan size |
| Business loan | Up to 1% of loan | ₹100 flat | Jan Seva Kendra on most loans |
| Insurance (motor, health) | 5% | Not offered now | Jan Seva Kendra |
| AEPS, money transfer, bills, PAN, travel, tax | ₹1 to ₹1,000 per service | Not offered | Jan Seva Kendra |
Jan Seva Kendra figures are from the commission chart published by the Jan Seva Kendra retailer portal (jansevakendra.org, September 2023). GroMo figures are the highest payout in each category in the GroMo product catalogue (GroMo catalogue, retrieved 2026-10-28). "Up to" means the highest product in that category; many products pay less.
How this comparison is ordered: products start with the ones where the gap is biggest (accounts and cards), then loans, and end with services only a Jan Seva Kendra offers.
1. Savings Account: Up to ₹5 vs Up to ₹600
Jan Seva Kendra: up to ₹5 per account | GroMo: up to ₹600 per account | Gap: about 120 times
Savings account opening shows the biggest gap. The Jan Seva Kendra chart pays up to ₹5 for a digital account with 10+ banks. The Kotak 811 Super Account pays GroMo partners ₹600 per successful account (GroMo catalogue, retrieved 2026-10-28).
| Jan Seva Kendra | GroMo | |
|---|---|---|
| Pay per account | Up to ₹5 | Up to ₹600 |
| 10 accounts | Up to ₹50 | Up to ₹6,000 |
| Paid when | Account opened | Account opened and bank conditions met |
How to earn this on GroMo:
- Pick a zero balance account like Kotak 811 in the GroMo app.
- Share the application link with a customer at your counter.
- Help them finish video or Aadhaar KYC on their own phone.
- Track the status in the app; the payout credits once the bank confirms.
Many walk-in customers still need a bank account they actually use. See our list of zero balance savings accounts to pick the right one.
2. Demat Account: Up to ₹100 vs Up to ₹550
Jan Seva Kendra: up to ₹100 | GroMo: ₹150 to ₹550 | Gap: up to 5 times
The Jan Seva Kendra chart pays up to ₹100 for a demat account. On GroMo, demat accounts pay ₹150 to ₹550 per account depending on the broker.
| Jan Seva Kendra | GroMo | |
|---|---|---|
| Pay per account | Up to ₹100 | ₹150 to ₹550 |
| 5 accounts | Up to ₹500 | Up to ₹2,750 |
How to earn this on GroMo:
- Choose a demat product in the GroMo app.
- Share the link with a customer asking about shares or IPOs.
- The customer completes KYC with PAN and Aadhaar.
- The payout credits after the broker marks the account successful.
3. Credit Card: Not on the Chart vs Up to ₹2,000
Jan Seva Kendra: no rate listed | GroMo: up to ₹2,000 per approved card | Gap: full payout on GroMo
The Jan Seva Kendra chart has a "Credit Card and Loan Apply" section, but it lists no credit card commission. On GroMo, the SBI Credit Card pays partners ₹2,000 per approved card (GroMo catalogue, retrieved 2026-10-28).
| Jan Seva Kendra | GroMo | |
|---|---|---|
| Pay per card | Not listed | Up to ₹2,000 |
| Number of cards | Not listed | 30+ cards from many banks |
| 3 approved cards | Not listed | Up to ₹6,000 |
Most cards pay less than the top rate, and the payout comes only when the bank approves the card. Our guide on credit card refer and earn explains how card payouts work.
How to earn this on GroMo:
- Check the customer's income and CIBIL basics first.
- Pick a card they are likely to get in the GroMo app.
- Share the link and help them apply.
- Track approval in the app.
4. FD-Backed Credit Card: Not on the Chart vs Up to ₹1,750
Jan Seva Kendra: no rate listed | GroMo: up to ₹1,750 | Best for: customers with no credit history
Many Jan Seva Kendra customers have savings but no credit card and no CIBIL score. A secured card against a fixed deposit suits them. The HDFC Secured Credit Card pays GroMo partners ₹1,750 per approved card (GroMo catalogue, retrieved 2026-10-28).
How to earn this on GroMo:
- Find customers who keep money in FDs but have no card.
- Explain that the card is backed by their own FD.
- Share the HDFC Secured or another secured card link.
- The payout credits after approval.
Read our full guide to the credit card against FD before you explain it to customers.
5. Investment and EMI Card: Not on the Chart vs Up to ₹1,000
Jan Seva Kendra: no rate listed | GroMo investment: up to ₹1,000 | GroMo EMI card: up to ₹600
The Jan Seva Kendra chart has no investment or EMI card products. On GroMo, the Axis Micro Investment pays partners ₹1,000 (GroMo catalogue, retrieved 2026-10-28).
The Bajaj Finserv Insta EMI card pays GroMo partners ₹600 per approved card (GroMo catalogue, retrieved 2026-10-28).
How to earn this on GroMo:
- Ask customers who come for pension or scheme work where their savings sit.
- Suggest a simple investment or FD product from the GroMo app.
- For shopping customers, suggest an EMI card.
- Track each case in the app.
6. Personal Loan: Which Pays More, 1% or ₹500 Flat?
Jan Seva Kendra: up to 1% of loan amount | GroMo: ₹100 to ₹500 per disbursed loan | Who wins: depends on loan size
Personal loans are the one financial product where the Jan Seva Kendra chart can pay more. It lists up to 1% of the loan amount. On GroMo, personal loans pay a flat ₹100 to ₹500 per disbursed loan, and the Lendingplate Personal Loan pays ₹500 (GroMo catalogue, retrieved 2026-10-28).
| Loan amount | Jan Seva Kendra (up to 1%) | GroMo (top flat payout) |
|---|---|---|
| ₹20,000 | Up to ₹200 | Up to ₹500 |
| ₹50,000 | Up to ₹500 | Up to ₹500 |
| ₹1,00,000 | Up to ₹1,000 | Up to ₹500 |
So for small instant loans below ₹50,000, GroMo's flat payout is usually higher. For loans above ₹50,000, the chart's 1% can be higher, if the full 1% is actually paid. GroMo also gives 25+ lenders, so a customer rejected by one lender can try another. Check the live payout in the GroMo app, as some lenders show a percentage there.
7. Business Loan: Up to 1% vs ₹100 Flat
Jan Seva Kendra: up to 1% | GroMo: ₹100 per disbursed loan | Who wins: Jan Seva Kendra on most loans
For business loans, the Jan Seva Kendra chart's up to 1% beats GroMo's flat ₹100 on most loans, since 1% of a ₹10,000 loan is already ₹100, which is the break-even point. If a shop owner needs working capital, compare both before you choose.
8. Services Only a Jan Seva Kendra Offers
AEPS: ₹0.25 to ₹10 | Money transfer: ₹3 to ₹30 | Tax filing: ₹100 to ₹1,000 | Insurance: 5%
GroMo does not offer AEPS, mini ATM, money transfer, bill payments, PAN, travel, registration or tax filing services. These are a Jan Seva Kendra's core business, and they bring the daily footfall.
| Service | Jan Seva Kendra (chart) | GroMo |
|---|---|---|
| AEPS withdrawal | ₹0.25 to ₹10 per transaction | Not offered |
| Money transfer | ₹3 to ₹30 per transfer | Not offered |
| Bill payment | ₹1 per bill | Not offered |
| PAN card | ₹5 to ₹9 | Not offered |
| Income tax return | ₹400 per return | Not offered |
| Motor and health insurance | 5% | Not offered now |
| Mobile recharge | 1% to 3% of amount | Not offered (Vi new connection pays up to ₹175) |
GroMo pays for new Vi prepaid connections and number ports, not for recharges. Vodafone Prepaid pays GroMo partners ₹175 per completed deal (GroMo catalogue, retrieved 2026-10-28). Read more about GroMo Instant Deals.
How Much More Can You Earn From the Same Customers?
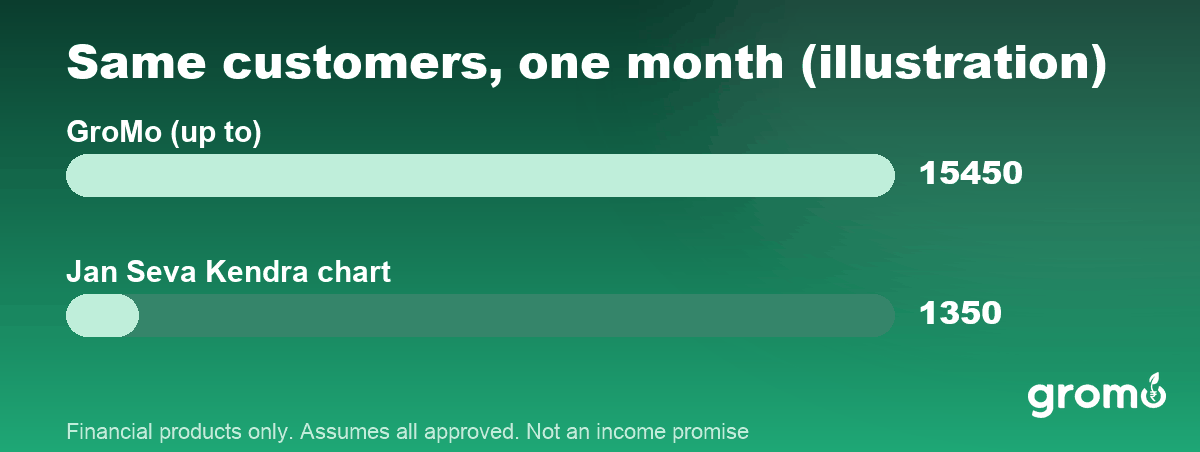
The real difference shows when the same walk-in customers are offered financial products. Here is an illustrative month for one counter.
| Work done | Jan Seva Kendra (chart) | GroMo (up to) |
|---|---|---|
| 10 savings accounts | ₹50 | ₹6,000 |
| 4 demat accounts | ₹400 | ₹2,200 |
| 2 credit cards | Not listed | ₹4,000 |
| 1 FD-backed credit card | Not listed | ₹1,750 |
| 3 personal loans of ₹30,000 | ₹900 | ₹1,500 |
| Total from financial products | ₹1,350 | ₹15,450 |
The GroMo column uses the top payout in each category and assumes every application is approved, so real earnings are usually lower. It is an illustration, not an income promise. Even so, the gap is large because banks pay more for an approved account or card than a portal pays per transaction.
Jan Seva Kendra vs GroMo: setup and joining
| Point | Jan Seva Kendra | GroMo |
|---|---|---|
| Joining | Official CSC: free, plus TEC exam fee; private portals set their own fees | Free |
| Shop | Needed | Not needed, works on your phone |
| Equipment | Computer, printer, fingerprint device, mini ATM (₹2,499 on the chart) | Smartphone only |
| Cash | Your own cash for AEPS and mini ATM | No cash handling |
| Training | Varies | Free training in the app |
| Payout | As per portal | To your bank account after approval |
Can a Jan Seva Kendra use GroMo at the same time?
Yes. GroMo is a separate, free app and does not replace your CSC or portal ID. You keep doing daily services for footfall, and offer GroMo products to the customers who need them. Our guide on CSC extra income gives a script for which customer to offer what.
Important Safety Tips
- Never force a product: offer a card or loan only when the customer needs it and can repay.
- Customer applies on their own phone: never fill forms with their OTP or fingerprint.
- Check payouts in the app: GroMo payouts are set by banks and change often.
- Verify any portal before paying: private "Jan Seva Kendra" portals are not government offices.
- Keep it separate: do not mix customer cash from AEPS with any financial product application.
Which Should You Choose: Jan Seva Kendra, GroMo or Both?
- Already run a Jan Seva Kendra? Keep it for daily services and add GroMo for accounts, cards and loans.
- No shop and no money to invest? Start with GroMo on your phone; you can add a CSC later.
- Want income from cash services? A Jan Seva Kendra or Bank Mitra CSP fits better.
- Customers asking for big business loans? Compare the chart's 1% with GroMo before choosing.
A Jan Seva Kendra brings people to your counter every day, and GroMo pays you well when those same people open an account, get a card or take a loan. Use both, and each customer becomes worth much more than a ₹1 bill payment.
GroMo is a free app where partners help customers apply for savings accounts, credit cards, loans and demat accounts from partner banks, and earn a commission on approval.
FAQ: Jan Seva Kendra vs GroMo Commission
Which pays more, Jan Seva Kendra or GroMo?
On financial products like savings accounts, demat accounts and credit cards, GroMo pays much more per customer. On daily services like AEPS, money transfer, bills and tax filing, only a Jan Seva Kendra pays.
How much does GroMo pay for a savings account?
Up to ₹600 per successful account on the top product, against up to ₹5 on the Jan Seva Kendra chart we compared.
Does a Jan Seva Kendra pay commission on credit cards?
The chart we compared lists no credit card commission. On GroMo, credit cards pay up to ₹2,000 per approved card.
Is the 1% loan commission better than GroMo?
For loans above ₹50,000, up to 1% can be higher than GroMo's flat payout. For smaller loans, GroMo's flat payout of up to ₹500 is usually higher.
Can I run a Jan Seva Kendra and GroMo together?
Yes. GroMo is free and separate. Many counter owners use it alongside their CSC or portal ID.
Do I need a shop for GroMo?
No. GroMo works from your phone, with no shop, equipment or cash needed.
Is GroMo free to join?
Yes. Joining and training are free. See how the GroMo app works for the steps.
GroMo (Vitrak Technologies Pvt Ltd) is a distribution platform. GroMo is not a bank, NBFC, insurer or investment adviser. All products are offered by their respective RBI, IRDAI or SEBI-regulated providers.
Partner earnings depend on effort, product mix and customer eligibility. Any figures shown are illustrative. They are not typical and are not promised.
Sources: GroMo product catalogue, commission rates by product, retrieved 2026-10-28. Jan Seva Kendra commission chart (PDF), jansevakendra.org, dated September 2023, retrieved 2026-10-28.
Disclaimer
GroMo has no connection with jansevakendra.org or any Jan Seva Kendra portal, and this article does not endorse any portal. Jan Seva Kendra figures are reproduced from that portal's chart dated September 2023 and may have changed; it is not an official Common Service Centre (CSC) rate card. GroMo commissions are set by partner banks, vary by product and campaign, and are paid only on approved applications; check the live commission in the GroMo app. The monthly example is an illustration, not an income promise. GroMo does not promise any level of income. GroMo is available only to users aged 18 and above. Everything above is general information, not financial advice.


