
Credit Card Against FD: Limit, Eligibility and Best Cards 2026
Credit card against FD: get 75% to 100% of your FD as limit, even with low or no CIBIL. Best secured cards, eligibility, charges and steps to apply.
A credit card against FD is a secured credit card that a bank gives you on the strength of your fixed deposit. Because the FD works as security, banks approve people with no income proof, no credit history or a low CIBIL score. You usually get a credit limit of 75% to 100% of the FD (issuer listings, retrieved 2026-10-14), and the FD keeps earning interest while the card is active. If a low score is your main worry, also read our guide on the credit card for low CIBIL score.
Below are the 6 best FD credit cards in India, what each one offers, and the steps to get one. All six are live on the GroMo app today, and where a card has limits or trade-offs, we say so plainly.
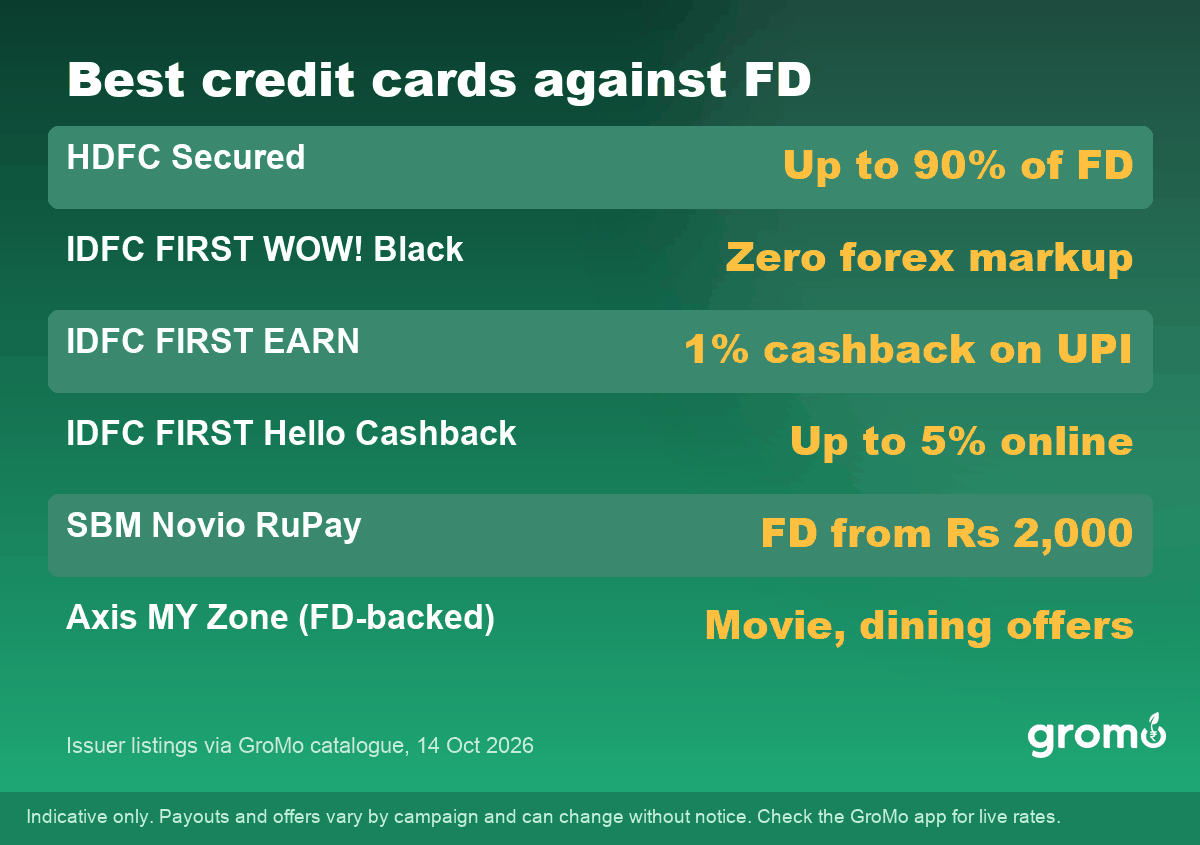
| Card | Limit vs FD | Minimum FD | Key benefit | Best for |
|---|---|---|---|---|
| HDFC Secured Credit Card | Up to 90% (max ₹8 lakh) | Set by bank | Big bank, 100% digital | First card from a large bank |
| IDFC FIRST WOW! Black | Linked to FD | Set by bank | Zero forex markup | Travel spends |
| IDFC FIRST EARN | Linked to FD | Set by bank | 1% cashback on UPI | Daily UPI spenders |
| IDFC FIRST Hello Cashback | 100% | Set by bank | Up to 5% cashback online | Online shoppers |
| SBM Novio RuPay | Linked to FD | ₹2,000 | Lifetime free, works on UPI | Students, first-timers |
| Axis Bank MY Zone (FD-backed) | Linked to FD | Set by bank | Movie and dining offers | Lifestyle spends |
Card features come from each issuer's product listing (GroMo catalogue, retrieved 2026-10-14). They change often, so check the bank's page before you apply.
How this list is ranked: each card is judged on three things only, how much of your FD you get as limit, how small an FD you can start with, and how useful the rewards are for everyday spends. Nothing else is used.
1. HDFC Secured Credit Card: Up to 90% of Your FD
Limit: up to 90% of FD, max ₹8 lakh | Journey: 100% digital | Best for: a first card from a big bank
The HDFC Secured Credit Card gives you a limit of up to 90% of your FD, with a cap of ₹8 lakh (HDFC Bank listing, retrieved 2026-10-14), one of the highest among secured cards. HDFC Bank is one of India's largest card issuers, so a clean record here helps when you later want an unsecured card or a loan from the same bank.
How to get the HDFC Secured Credit Card:
- Open the application and enter your mobile number and PAN.
- Complete Aadhaar e-KYC with the OTP on your Aadhaar-linked mobile.
- Book the FD for the limit you want, or pick an existing HDFC FD.
- Accept the lien on the FD and wait for the card.
2. IDFC FIRST WOW! Black: Zero Forex Markup
Rewards: 4 points per ₹150, bonus points on hotels and flights | Forex markup: zero | Best for: travel
The IDFC FIRST WOW! Black is an FD-backed card with zero forex markup, which is rare even on unsecured cards. The listing says no income proof or CIBIL score is needed, and a virtual card is issued right after approval. You also get a monthly movie discount and a fuel surcharge waiver.
How to get the IDFC FIRST WOW! Black:
- Start the application and fill in your basic details.
- Finish video or Aadhaar KYC.
- Book an FD with IDFC FIRST Bank for your chosen amount.
- Get the virtual card and start using it.
3. IDFC FIRST EARN: 1% Cashback on UPI
Rewards: 1% cashback on eligible UPI spends | Cap: ₹500 per statement cycle | Best for: daily UPI spenders
The IDFC FIRST EARN card pays you back on the UPI payments you already make through the IDFC FIRST app, up to ₹500 every statement cycle (IDFC FIRST listing, retrieved 2026-10-14). The card is FD-backed, carries welcome cashback offers and gives you an instant virtual card after approval, so you can use it the same day.
How to get the IDFC FIRST EARN card:
- Apply with your mobile number, PAN and Aadhaar.
- Complete e-KYC.
- Book the FD for the limit you want.
- Link the card in the IDFC FIRST app to use it on UPI.
4. IDFC FIRST Hello Cashback: Up to 5% Cashback Online
Limit: 100% of FD | Rewards: up to 5% online, 1% on UPI and offline | Joining fee: ₹0 (introductory offer)
The IDFC FIRST Hello Cashback card gives a limit equal to 100% of your FD (IDFC FIRST listing, retrieved 2026-10-14) and cashback rates close to unsecured cashback cards. You get up to 5% back on online spends and up to 6% on hotels and flights booked in the IDFC FIRST app, plus roadside assistance and a fuel surcharge waiver.
How to get the IDFC FIRST Hello Cashback card:
- Start the application online.
- Finish KYC with PAN and Aadhaar.
- Book the FD, and your limit will match it.
- Activate the card and set your PIN.
5. SBM Novio RuPay: Start With a ₹2,000 FD
Minimum FD: ₹2,000 | Fee: lifetime free | Network: RuPay, works on UPI
The SBM Novio RuPay card lets you start with an FD of just ₹2,000 (SBM Bank listing, retrieved 2026-10-14), which makes it one of the easiest first credit cards in India. It is lifetime free and, because it runs on RuPay, you can link it to UPI and pay at any shop QR code. The listing also mentions movie and fuel offers.
How to get the SBM Novio card:
- Apply with your mobile number and PAN.
- Complete Aadhaar e-KYC.
- Open an FD starting from ₹2,000.
- Get the card and link it to your UPI app.
6. Axis Bank MY Zone (FD-backed): Movie and Dining Offers
Rewards: 25% cashback on BookMyShow, EDGE points | Fuel: 1% surcharge waiver, up to ₹400 a month | Dining: up to 20% off at partner restaurants
The FD-backed Axis Bank MY Zone card gives lifestyle offers that you usually see on paid cards, while the FD takes care of approval. It suits people who spend on movies and eating out, and it helps build a credit score from the very first bill.
How to get the Axis MY Zone (FD-backed) card:
- Apply online with your basic details.
- Finish KYC.
- Book the FD with Axis Bank.
- Get the card and start with small spends.
How Does a Credit Card Against FD Work?
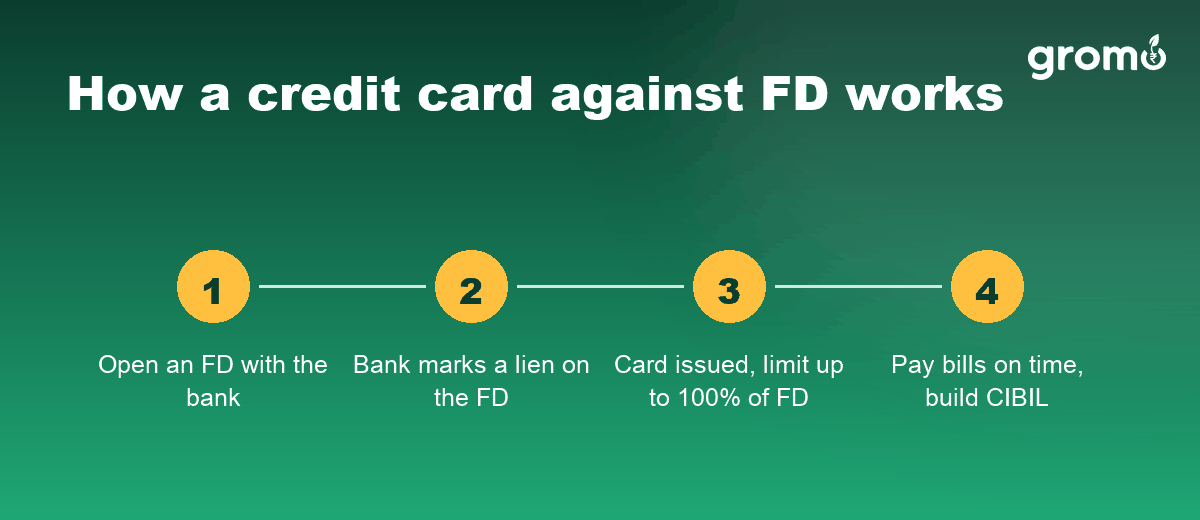
A credit card against FD works like any normal credit card. Only the approval route is different: the bank marks a lien on your FD, so you cannot break it while the card is active, and it can recover unpaid dues from the FD if you stop paying for a long time. New to deposits? Read what a fixed deposit is.
How much credit limit do you get on an FD?
You get a credit limit of 75% to 100% of your FD amount on most secured cards. The bank sets the exact percentage.
| FD amount | Limit at 80% | Limit at 90% | Limit at 100% |
|---|---|---|---|
| ₹10,000 | ₹8,000 | ₹9,000 | ₹10,000 |
| ₹25,000 | ₹20,000 | ₹22,500 | ₹25,000 |
| ₹50,000 | ₹40,000 | ₹45,000 | ₹50,000 |
| ₹1,00,000 | ₹80,000 | ₹90,000 | ₹1,00,000 |
Need a bigger limit later? Most banks let you add to the FD or open a second one, and the limit grows to match.
FD credit card eligibility and documents
Almost any Indian resident aged 18 or above with valid KYC can get a credit card against FD. Most cards need no salary slip, no ITR and no minimum credit score.
- Age 18 years or above (some banks ask for 21)
- PAN card and Aadhaar card, with a mobile number linked to Aadhaar
- An FD with the same bank, or money to open one
- A selfie or video KYC on some digital journeys
The bank still runs its own KYC and fraud checks, so approval is much easier than on a normal card but never automatic.
Does an FD credit card improve your CIBIL score?
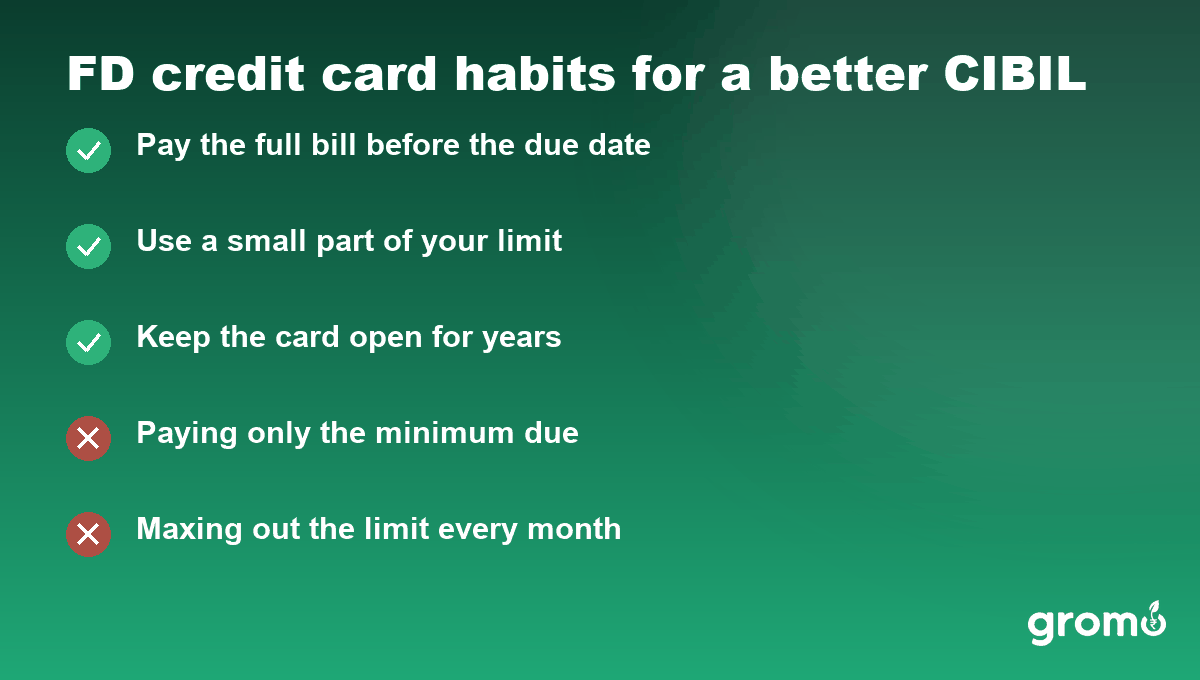
Yes. A credit card against FD is reported to credit bureaus like CIBIL just like a normal card, so it builds your score when you pay on time. Most people see a score form in 6 to 12 months of clean use, and many banks then offer an unsecured card. Our guide on how to improve your credit score covers the habits that help most.
Charges on a secured credit card
| Charge | What to expect |
|---|---|
| Interest on unpaid bill | Same as normal cards, very high |
| Late payment fee | Slab-based, grows with the bill amount |
| Cash withdrawal | Fee plus interest from day one |
| Joining or annual fee | Zero on many FD cards, check yours |
| FD lien | You cannot break the FD while the card is active |
FD credit card vs normal credit card
| Point | FD credit card | Normal credit card |
|---|---|---|
| Security | Your FD | None |
| Income proof | Usually not needed | Needed |
| CIBIL score | Not needed on most | Usually needs a good score |
| Credit limit | Linked to FD | Based on income and score |
| Rewards | Basic to good | Basic to premium |
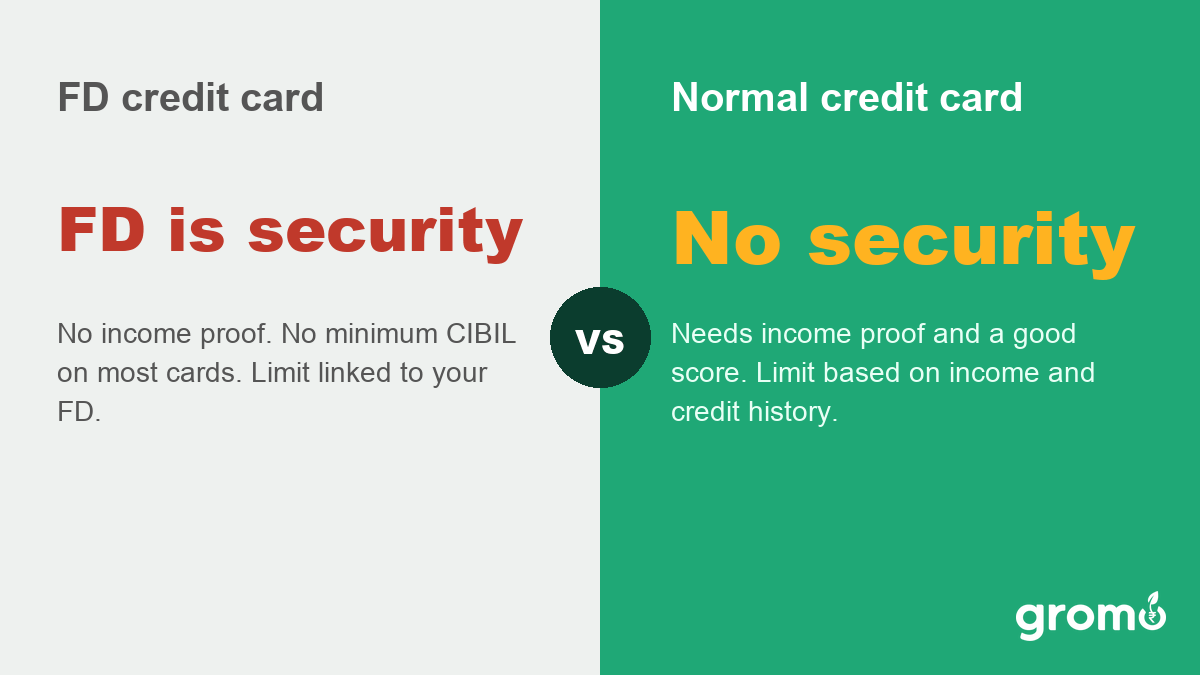
Pick an FD card if you are new to credit, have a low score or have no income proof, then move to a normal card once your score is strong. Our guide to the types of credit cards explains the other options.
Important Safety Tips
- Pay the full bill every month: the FD protects the bank, not you. Card interest is many times what your FD earns, so never carry a balance.
- Keep the FD running: book it for at least 1 year or choose auto-renewal. If the FD closes, the card may be blocked.
- Know the lien: in an emergency you must clear the dues and close the card before you can use the FD money.
- Apply only on official pages: never pay anyone a "processing fee" to get a secured card approved.
Which FD Credit Card Should You Pick?
- Want a big bank and a high limit? HDFC Secured Credit Card, up to 90% of FD.
- Travel or spend abroad? IDFC FIRST WOW! Black, with zero forex markup.
- Pay mostly by UPI? IDFC FIRST EARN, or SBM Novio RuPay if you want to start small.
- Shop online a lot? IDFC FIRST Hello Cashback.
- Only have a few thousand rupees to spare? SBM Novio, from a ₹2,000 FD.
A credit card against FD is the honest first step into credit: no income proof, low risk, and a real chance to build your score in under a year. Pick the card that matches how you already spend, pay in full every month, and upgrade once your score is strong.
You can also earn by helping others get one. GroMo is a free app where partners help customers apply for cards, loans and bank accounts, and earn a commission on approval. The HDFC Secured Credit Card pays partners ₹1,750 per approved card (GroMo catalogue, retrieved 2026-10-14).
The IDFC WOW! Black Credit Card pays partners ₹500 per approved card (GroMo catalogue, retrieved 2026-10-14).
FAQ: Credit Card Against FD
What is the minimum FD for a credit card?
The minimum FD depends on the bank. Some cards, like SBM Novio, start from ₹2,000. Many banks ask for more.
How much credit limit will I get against my FD?
Usually 75% to 100% of the FD amount. HDFC Secured gives up to 90% with a ₹8 lakh cap.
Can I get a credit card against FD with a low CIBIL score?
Yes. Most FD cards do not need a minimum CIBIL score because your FD covers the bank's risk. The bank still does KYC and fraud checks.
Does my FD earn interest when it is linked to a credit card?
Yes. Your FD keeps earning interest at the normal rate. It is only locked with a lien, so you cannot break it while the card is active.
Can students get a credit card against FD?
Yes. Any resident aged 18 or above with PAN, Aadhaar and an FD can usually apply. No income proof is needed.
What happens if I do not pay my FD credit card bill?
You pay interest and late fees like any card. If you keep missing payments, the bank can recover the dues from your FD and report the default to credit bureaus.
Can I close the FD credit card and get my FD back?
Yes. Pay the full outstanding, ask the bank to close the card, and the lien is removed. You can then break or keep the FD.
How can I earn by referring FD credit cards?
Join GroMo as a partner for free, share the card link with people who want a secured card, and earn when the bank approves the card. See how the GroMo app works for the steps.
GroMo (Vitrak Technologies Pvt Ltd) is a distribution platform. GroMo is not a bank, NBFC, insurer or investment adviser. All products are offered by their respective RBI, IRDAI or SEBI-regulated providers.
Partner earnings depend on effort, product mix and customer eligibility. Any figures shown are illustrative. They are not typical and are not promised.
Sources: GroMo product catalogue, secured credit card listings and commission rates, retrieved 2026-10-14. Card features, limits and fees are set by each issuing bank and change without notice; check the bank's current terms.
Disclaimer
GroMo does not promise any level of income. Card approval, credit limit, interest rates and fees are at the sole discretion of the issuing bank. GroMo commissions are set by partner banks, vary by product and campaign, and are paid only on approved applications; check the live commission in the GroMo app. GroMo is available only to users aged 18 and above. Everything above is general information, not financial advice.


