
Loan Leads for DSA: How to Find Genuine Loan Customers (2026)
Loan leads for DSA: 9 ways to find genuine personal and business loan customers, free vs paid leads, how to qualify a lead, and TRAI rules to follow.
The best loan leads for DSA agents come from people who already trust you: past customers, local shop owners, CAs, property dealers and your own network, plus a little local digital marketing. Bought lead lists are usually old, shared with many agents and risky under India's data and telemarketing rules, so treat them as a last resort. A genuine lead is someone who needs a loan now, meets the lender's basic eligibility and agrees to be contacted. Selling cards too? Read our guide on credit card leads.
Below are 9 lead sources ranked by how well they convert, how to qualify a lead before you apply, and the rules every loan agent must follow. Where a source has trade-offs, we say so plainly.
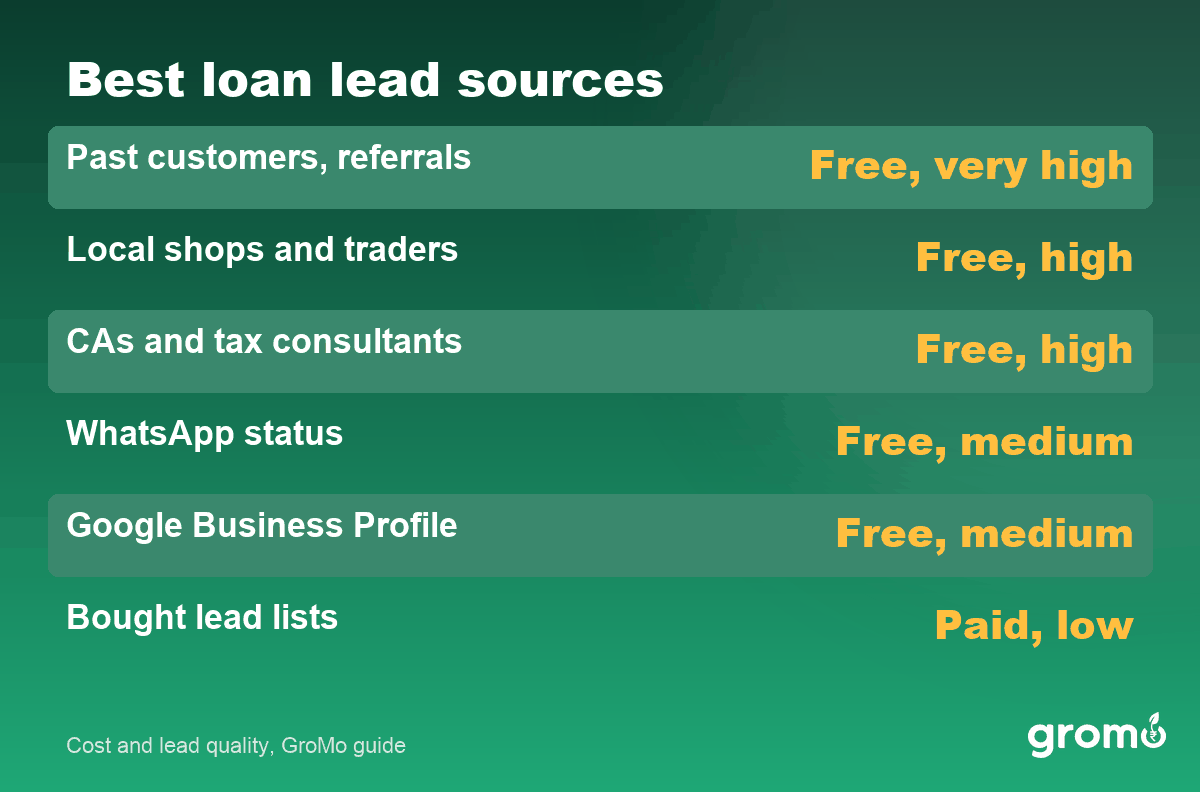
| Lead source | Cost | Lead quality | Best for |
|---|---|---|---|
| Past customers and referrals | Free | Very high | Every DSA |
| Local shop owners and traders | Free | High | Business and personal loans |
| CAs and tax consultants | Free, sometimes a share | High | Business loans, self-employed |
| Property dealers and builders | Share of payout | High | Loan against property, home-related |
| Employers and HR contacts | Free | High | Salaried personal loans |
| WhatsApp status and groups | Free | Medium | Personal loans, cards |
| Google Business Profile | Free | Medium to high | Local loan searches |
| Local social media ads | Paid | Medium | Volume in one area |
| Bought lead lists | Paid | Low | Not recommended |
How this list is ranked: each source is judged on three things only, how often its leads get approved, how much it costs, and how safe it is under India's data and calling rules. Nothing else is used.
1. Past Customers and Referrals: The Highest-Quality Leads
Cost: free | Approval rate: highest | Effort: a call after every disbursal
A customer whose loan you got approved is your best source of new leads. They already trust you, and their friends, relatives and colleagues often need loans too. Ask every happy customer for 2 referrals right after disbursal, when they are most satisfied.
How to build referrals:
- Call the customer after disbursal to check everything went well.
- Ask if anyone they know needs a loan, card or account.
- Send a short WhatsApp message they can forward.
- Thank them when a referral gets approved.
2. Local Shop Owners and Traders: Steady Business Loan Leads
Cost: free | Lead type: business loans, personal loans, credit lines | Best time: before festivals and stock season
Kirana stores, medical shops, mobile shops and small traders need working capital, especially before festivals. Visit the market in person, introduce yourself and leave your number. Shop owners also meet hundreds of customers a week and can refer people to you.
How to work local markets:
- Pick one market and visit the same shops every month.
- Ask what they need: stock money, a card or an account.
- Offer to help their staff with salary accounts or personal loans.
- Keep a simple notebook or sheet of every shop and its need.
3. CAs and Tax Consultants: Self-Employed Leads
Cost: free or a small share | Lead type: business loans, self-employed personal loans | Peak: ITR filing season
CAs and tax consultants know which clients are growing and need funds. They also hold the ITRs and bank statements lenders ask for. A tie-up where you handle the loan process and they handle the paperwork works well for both sides.
How to tie up with a CA:
- Meet 3 to 5 local CAs and explain what loans you offer.
- Agree how you will work together in writing.
- Share status updates so the CA can update their client.
- Never ask the CA for client data without the client's consent.
4. Property Dealers and Builders: Bigger Ticket Leads
Cost: usually a share of your payout | Lead type: loan against property, home-related loans | Ticket size: large
Property dealers meet buyers and sellers who need loans. If you offer loans against property or home-related products, a dealer tie-up brings fewer but larger cases. Agree on any sharing arrangement in writing before the first case.
5. Employers and HR Contacts: Salaried Personal Loan Leads
Cost: free | Lead type: salaried personal loans, credit cards, salary accounts | Approval: high for stable salaries
Salaried employees at local companies, hospitals, schools and factories are good personal loan customers. A friendly contact in HR or a staff association can let you hold a short help desk on payday. Offer accounts and cards too, not just loans.
6. WhatsApp Status and Groups: Free Daily Reach
Cost: free | Lead type: personal loans, cards | Rule: share only with people who know you
Post a simple status every week explaining one product, like an instant personal loan or a lifetime free card. Share in groups only where sharing is allowed. Never add people to groups without their consent and never spam strangers. Our guide on selling credit cards through WhatsApp has message templates you can adapt.
7. Google Business Profile: People Searching Near You
Cost: free | Lead type: people searching "loan agent near me" | Needs: an office or service area
People search for nearby loan agents every day. A free Google Business Profile with your service area, phone number, hours and real customer reviews helps them find you. Add photos of your office and keep your hours accurate.
How to set it up:
- Create a free Google Business Profile.
- Add your services, area and contact number.
- Ask happy customers to leave honest reviews.
- Reply to every review and question.
8. Local Social Media Ads: Paid Volume in One Area
Cost: paid | Lead type: personal loans, cards | Tip: target a small area and a clear offer
Small, local Facebook or Instagram ads aimed at your city can bring steady enquiries. Keep the message honest: no "guaranteed loan" or "no documents" claims. Call every lead quickly, as interest drops within hours.
9. Bought Lead Lists: Should You Buy Them?
Cost: paid | Quality: low | Risk: data and telemarketing rules
Lead lists sold online are a poor bet (DPDP Act 2023 requires consent). They are usually old, shared with many agents and gathered without clear consent. India's Digital Personal Data Protection Act, 2023 requires consent to process personal data, and its rules notified in November 2025 are being phased in (DPDP Rules 2025, PIB, November 2025). Calling strangers for promotions from a normal mobile number also breaks TRAI rules.
How to Qualify a Loan Lead Before You Apply
A qualified lead saves you time and protects the customer's credit score. Each rejected application leaves a hard enquiry on the customer's credit report, so check the basics first.
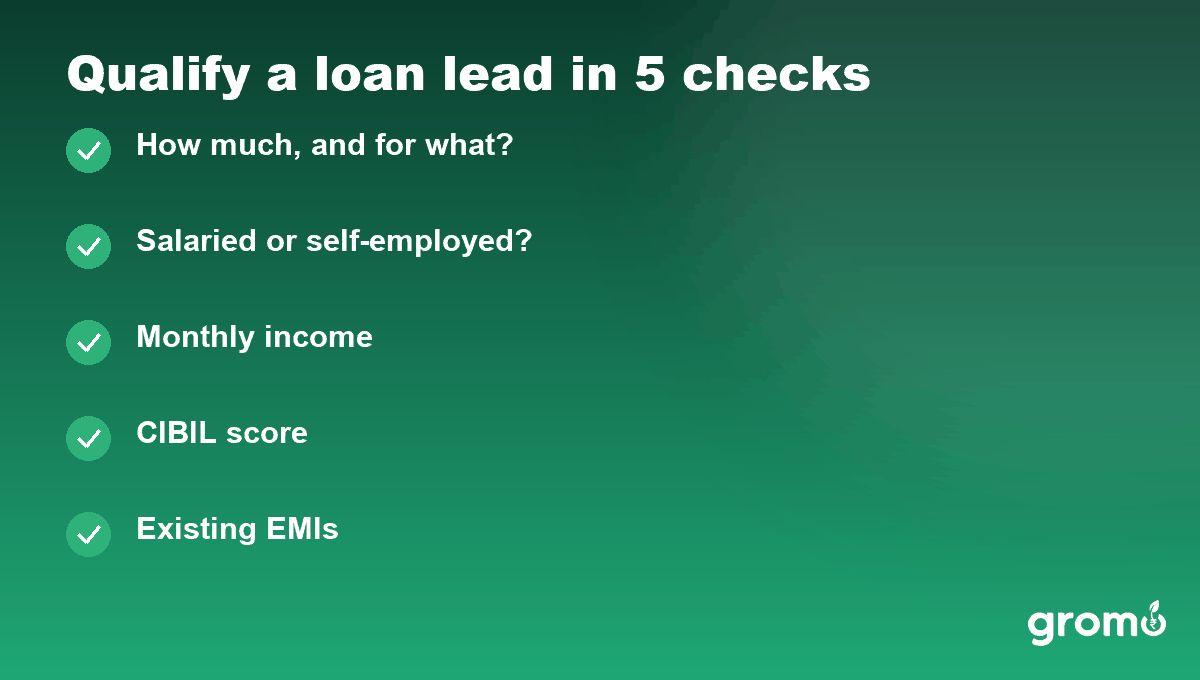
Five questions to ask every lead
- How much do you need, and for what? The purpose decides the product.
- Are you salaried or self-employed? It decides the lender and documents.
- What is your monthly income? Lenders have minimum income rules.
- Do you know your CIBIL score? Low scores need different lenders or a secured card first.
- Do you have existing EMIs? High EMIs reduce how much a lender will approve.
Match the lead to the right lender
Do not send every lead to the same lender. Instant loan apps suit small, quick needs. Banks suit salaried people with good scores. A customer with a weak score may do better with a credit card against FD to build credit first.
Personal loan leads vs business loan leads
| Point | Personal loan lead | Business loan lead |
|---|---|---|
| Customer | Salaried or self-employed person | Shop or business owner |
| Key proof | Salary slips or ITR, bank statement | ITR, GST, business bank statement |
| Ticket size | Small to medium | Medium to large |
| Best sources | Employers, referrals, WhatsApp | Shops, CAs, traders |
What Rules Must a Loan Agent Follow When Contacting Leads?
India's calling and data rules tightened in 2025 and 2026, and they apply to loan agents.
TRAI telemarketing rules
Under TRAI's amended telemarketing regulations notified in February 2025, promotional calls must use the 140 number series and service or transactional calls use the 1600 series. Ordinary 10-digit mobile numbers cannot be used for telemarketing (TRAI press release 11/2025, February 2025). Personal calls to people who already know you and asked for help are different from cold promotional calls.
Consent and customer data
Collect only the details you need, with the customer's permission, and use them only for their application. Never share a customer's documents or number with another agent. The DPDP Rules 2025 phase in notice and consent duties by 2027 (DPDP Rules 2025, PIB, November 2025), so building consent habits now protects you.
Never charge the customer
Genuine loan agents are paid by the lender. Asking a lead for a processing or approval fee before a loan is the most common loan scam pattern, and it destroys trust in every honest agent.
Important Safety Tips
- No guaranteed approval claims: the lender decides, not you.
- No cold spam: contact only people who know you or asked to be contacted.
- No fees from customers: your commission comes from the lender.
- Keep documents safe: share KYC only through the lender's official app or form.
- Track every lead: a simple sheet with name, need, status and next call date doubles conversions.
Which Lead Source Should You Start With?
- Brand new agent? Start with your own network and referrals, then add WhatsApp status.
- Work in a town market? Visit shops every month; they bring business loan leads.
- Good with numbers and paperwork? Tie up with 2 or 3 local CAs.
- Want online enquiries? Set up a Google Business Profile before spending on ads.
- Tempted to buy a lead list? Skip it; the quality is low and the risk is high.
Good loan leads come from trust, not from lists. Pick two sources from this guide, work them every week, qualify each lead before you apply, and your approval rate and income will both rise.
GroMo is a free app where partners help customers apply for personal loans, credit cards and bank accounts from 25+ lenders and banks, and earn a commission on approval. On GroMo, personal loans pay ₹100 to ₹500 per disbursed loan, depending on the lender (GroMo catalogue, retrieved 2026-10-28). If you are still deciding how to set up as an agent, read what a DSA code is and whether you need one.
FAQ: Loan Leads for DSA
How can a DSA get loan leads for free?
The best free sources are past customers and their referrals, local shop owners, CAs, employers' HR contacts, WhatsApp status and a free Google Business Profile.
Should I buy loan leads?
Usually no. Bought lists are often old, shared with many agents and collected without clear consent, which also creates risk under India's data and telemarketing rules.
How do I convert more loan leads?
Qualify each lead first: ask about the loan purpose, income, job type, CIBIL score and existing EMIs, then match the customer to a suitable lender.
Can I call loan leads from my mobile number?
You can call people who know you or asked you to call. Promotional calls to strangers from a normal 10-digit number are not allowed under TRAI rules; telemarketers must use the 140 series.
Where can I get business loan leads?
Local shop owners, traders, CAs and tax consultants are the best sources, especially before festivals and during ITR filing season.
Can a DSA charge a fee to the customer?
No. A genuine DSA is paid by the lender. A loan agent asking for an upfront fee is a common scam sign.
Which app helps a DSA earn from loan leads?
Partner apps like GroMo let you refer leads to many lenders and earn per approved case. See how the GroMo app works.
GroMo (Vitrak Technologies Pvt Ltd) is a distribution platform. GroMo is not a bank, NBFC, insurer or investment adviser. All products are offered by their respective RBI, IRDAI or SEBI-regulated providers.
Partner earnings depend on effort, product mix and customer eligibility. Any figures shown are illustrative. They are not typical and are not promised.
Sources: TRAI press release 11/2025 on telemarketing regulations (February 2025); Digital Personal Data Protection Rules 2025, PIB (November 2025); GroMo product catalogue, retrieved 2026-10-28.
Disclaimer
GroMo does not promise any level of income. Lead sources, approval rates and commissions vary by lender, product and customer profile. Follow TRAI telemarketing rules and data protection law when contacting customers, and always take consent. GroMo commissions are set by partner lenders, vary by product and campaign, and are paid only on approved or disbursed cases; check the live commission in the GroMo app. GroMo is available only to users aged 18 and above. Everything above is general information, not legal or financial advice.


