
What Is No Cost EMI? Meaning, Real Charges and How It Works
No cost EMI meaning: pay in instalments with no visible interest. What is no cost EMI, the charges you still pay, GST, and how to get it without a credit card.
By Arvind Kumar · Published 9 October 2026 · Updated 9 October 2026
What is no cost EMI? It is an instalment plan where you repay only the product price, split across months, with no interest shown on your statement. A 24,000-rupee phone on a 6-month no cost EMI bills 4,000 a month. The interest has not vanished, though. The seller usually absorbs it as an upfront discount you give up, and you may still pay a processing fee and GST on the interest component. No cost EMI is cheaper than a regular EMI, but it is rarely free.
Key takeaways- No cost EMI meaning: you repay the sticker price in equal instalments, with the interest covered by a discount the seller funds. - You can still pay a processing fee and, on some plans, GST charged on the interest the bank waives. - Compare the no cost EMI price against the upfront cash discount. Often you cannot have both. - You do not always need a credit card. Debit card EMI and EMI cards cover the rest. - Referring an EMI card through GroMo pays up to ₹600 per approved case (GroMo product catalogue, retrieved 2026-10-09).
What is no cost EMI? The meaning in plain terms
No cost EMI is a marketing name for a product bought on instalments where the lender's interest is paid by someone other than you, usually the brand or the retailer.
Definition — EMI. Equated Monthly Instalment: a fixed monthly repayment covering principal and interest over a set tenure. The EMI guide covers how instalments are calculated generally.
Definition — no cost EMI. An EMI where the interest charged by the lender is offset, so the sum of your instalments equals the product's listed price.
The lender still earns its interest; the brand funds it to close the sale. That is the whole mechanism, and understanding it tells you where to look for the real cost.
How does no cost EMI work?
- You pick the product and choose no cost EMI at checkout.
- The bank funds the purchase and charges its normal rate of interest on the amount.
- The brand pays that interest to the bank as a subvention, or gives an equivalent discount that cancels it.
- Your card is billed the full price, split into equal monthly instalments.
- You repay the instalments with no interest line on your statement.
The bank is paid. The brand has paid. The only person who sees a round number is you.
Is no cost EMI really free?
Usually not entirely. Three costs survive, and they are easy to miss.
| What you may still pay | Typical form |
|---|---|
| Processing fee | A one-time charge added to the first instalment |
| GST on the waived interest | Charged on the interest component even when the interest itself is waived |
| The discount you gave up | The cash price is often lower than the no cost EMI price |
The forfeited discount is the one that costs most and appears on no statement. If a phone sells for 24,000 outright or 24,000 across six instalments, but a 2,000 instant discount applies only to full payment, then the no cost EMI effectively cost you 2,000.
Always compare the final amount paid both ways, not the monthly figure.
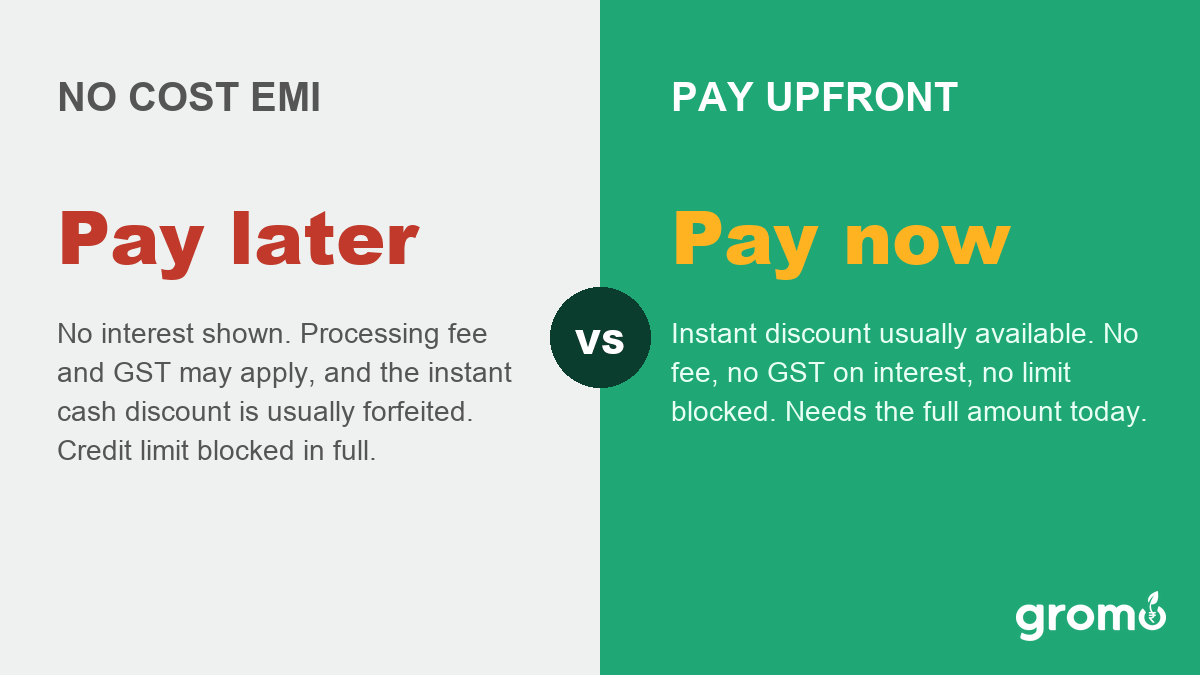
The cost of a no cost EMI is usually the discount you did not take. Image: GroMo.
No cost EMI vs regular EMI vs paying upfront
| No cost EMI | Regular EMI | Pay upfront | |
|---|---|---|---|
| Interest you see | None | Charged monthly | None |
| Who pays the interest | Brand or retailer | You | Nobody |
| Processing fee | Often yes | Usually yes | No |
| Instant discount | Often forfeited | Often forfeited | Usually available |
| Credit limit blocked | Yes | Yes | No |
| Best when | Cash is tight and no discount is offered | Nothing else is available | A cash discount exists |
One detail people miss: an EMI purchase blocks your credit limit for the full amount from day one, not instalment by instalment. A 60,000 purchase on a 1,00,000 limit leaves 40,000 available until you repay.
Can I get no cost EMI without a credit card?
Yes. A credit card is the most common route but not the only one.
- Debit card EMI. Many banks pre-approve debit card EMI for existing customers. HDFC, ICICI, SBI and others run this, and eligibility is usually visible at checkout or by SMS.
- EMI cards. A dedicated card issued by a consumer-finance lender for instalment purchases, with a pre-approved limit.
- Buy Now Pay Later. Shorter tenures, smaller amounts. What BNPL is covers that product separately.
- Consumer durable loans arranged in-store at the point of sale.
Definition — EMI card. A card carrying a pre-approved instalment limit at partner retailers, letting you buy on EMI without a credit card. The Bajaj Finserv Insta EMI card is the most widely used in India.
What to check before choosing no cost EMI
Compare the all-in price. Add the processing fee and GST to the instalment total, then set it against the cash price after any instant discount.
Check the tenure. Three, six and nine months are common. Longer tenures sometimes drop the no cost benefit entirely.
Confirm your limit can take it. The whole amount is blocked, which matters if you were counting on that headroom. Raising your credit card limit is a separate question worth settling first.
Read the cancellation terms. If you return the product, the waived interest is sometimes reclaimed.
Earn by referring EMI and credit line products with GroMo
GroMo is an Indian financial-products distribution platform where individuals refer products from partner banks and NBFCs and earn a commission on approved referrals.
EMI cards and credit lines sit in the catalogue alongside credit cards and loans. Current commissions (GroMo product catalogue, retrieved 2026-10-09):
| Product | Commission per approved referral |
|---|---|
| Bajaj Finserv Insta EMI card | ₹600 |
| FatakPay | ₹150 |
| HDFC Smart EMI | ₹100 |
| BharatPe Credit Line on UPI | ₹100 |
Commission rates are campaign-linked and change without notice (catalogue read 9 October 2026). The live rate in the app at the time of referral is the one paid.
EMI cards convert well because the customer does not need to want a loan. They want the phone, and the EMI card is simply how they get it. For the broader card range, types of credit cards sets out the options.
Frequently asked questions
Below are the questions people most often ask alongside this one.
What is no cost EMI in simple words?
No cost EMI lets you pay for a product in equal monthly instalments that add up to the listed price, with no interest shown. The lender's interest is funded by the brand or retailer rather than waived entirely.
What is the meaning of no cost EMI?
The meaning is an instalment plan with no visible interest charge to you. The total of your instalments equals the product's price, because a discount from the seller offsets the bank's interest.
Is no cost EMI really free?
Rarely completely. You may pay a processing fee and GST on the interest component, and you usually forfeit the instant cash discount available on full payment. Compare the total paid, not the monthly instalment.
Does no cost EMI affect my credit score?
Lenders report the EMI like any other borrowing. Paying on time helps your score, and missing instalments hurts it in the same way a missed card payment would.
Can I get no cost EMI without a credit card?
Yes. Debit card EMI, EMI cards and consumer durable loans all offer instalment purchases without a credit card, subject to the lender's eligibility checks.
What is an EMI card?
An EMI card carries a pre-approved instalment limit usable at partner retailers. It lets you buy on EMI without a credit card, with the limit set by the issuing lender.
Is GST charged on no cost EMI?
On some plans, yes. GST can apply to the interest component even where the interest itself is subsidised. Check the checkout breakup before confirming.
Summary
No cost EMI means repaying the product's listed price in equal instalments with no interest shown on your statement, because the brand or retailer funds the lender's interest. It is not usually free: a processing fee, GST on the interest component, and the forfeited cash discount are the three real costs. Compare the all-in total against paying upfront, and remember a credit card is not the only route.
Disclosures
GroMo (Vitrak Technologies Pvt Ltd) is a distribution platform. GroMo is not a bank, NBFC, insurer or investment adviser. All products are offered by their respective RBI, IRDAI or SEBI-regulated providers.
Partner earnings depend on effort, product mix and customer eligibility. Any figures shown are illustrative examples of individual results. They are not typical and are not guaranteed. GroMo does not guarantee any level of income.
Charges, fees, tenures and eligibility for EMI plans are set by the lender and the retailer, vary by offer, and change without notice. The examples here are illustrative. Check the exact breakup shown at checkout before confirming any purchase.
Written by Arvind Kumar. Published 9 October 2026. Last updated 9 October 2026.
Sources
- GroMo product catalogue, commission rates by product. Read 9 October 2026.
- Illustrative price and instalment examples are arithmetic for explanation only and are not quotations from any lender or retailer.


