
How to Increase Credit Card Limit: The Method That Works (2026)
How to increase credit card limit in India: the method banks reward, plus exact steps for SBI Card, ICICI, HDFC and Axis, RBI consent rules, and what to do if rejected.
To increase your credit card limit, you have two routes: accept a pre-approved limit increase offer from your bank, which usually needs no documents and is approved instantly, or request an increase yourself by sharing proof of higher income.
The method that works best is making your card look like a low-risk, high-value account for 6 to 12 months first: use it regularly, keep usage under 30 percent of the limit, and always pay the full bill on time. Banks then offer increases on their own.
By RBI rules, no bank can raise your limit without your explicit consent, so every increase needs your OTP or written approval. Below is the exact process for SBI Card, HDFC, ICICI, and Axis, plus what to do if your request is rejected.
Credit card limit increase: quick facts
| Question | Quick answer |
|---|---|
| Fastest way | Accept a pre-approved offer in your bank's app, often instant with no documents |
| When to ask | After 6 to 12 months of on-time payments (ICICI's terms say 12 months) |
| Documents if you request | Salary slips (salaried), ITR and bank statements (self-employed) |
| Cost | Usually free, HDFC states no charges for limit enhancement |
| Can the bank increase it without asking? | No, RBI requires your explicit consent for every increase |
| Effect on credit score | A higher limit lowers your utilisation ratio, which usually helps your score |
The method that actually works
Banks do not raise limits because you ask nicely. They raise them when your account data shows you can handle more credit. This four-step method is how you build that data, and it is the most reliable answer to how to increase my credit card limit.
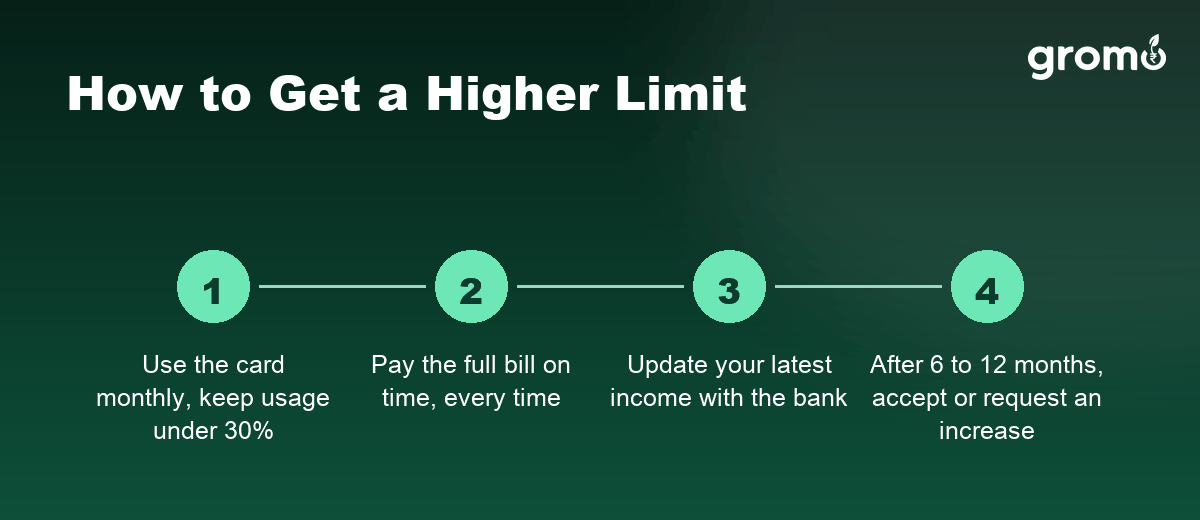
- Use the card every month. An unused card gives the bank no reason to lend you more. Put regular expenses like groceries, fuel, and bills on it.
- Keep usage under 30 percent of the limit. On a Rs 50,000 limit, keep monthly spends under Rs 15,000. Constantly maxing out the card signals financial stress and works against you.
- Pay the full bill before the due date. Paying only the minimum due keeps the account current, but banks read it as a sign of strain. Full, on-time payment is the single strongest signal.
- Update your income with the bank. Got a raise or a new job? Banks set limits partly on income they have on record, and stale income data caps your limit.
Do this for 6 to 12 months and most banks start showing pre-approved limit increase offers in their app. If one does not appear, request it yourself using the steps below.
Your rights: RBI's consent rule
Under the RBI's 2022 Master Direction on credit and debit cards, card issuers "shall not unilaterally upgrade credit cards and enhance credit limits." Your explicit consent is required every time, either written or digital with multi-factor authentication, which is why banks ask you to confirm with an OTP.
The same rules say your sanctioned limit cannot be breached at any point without your consent. Limit reductions do not need your consent, but the bank must inform you when it lowers your limit.
How to increase your credit card limit, bank by bank
SBI Card
SBI Card regularly identifies select cardholders for a pre-approved limit increase based on its internal credit policy, and these offers need no additional documents. To check for and accept an offer:
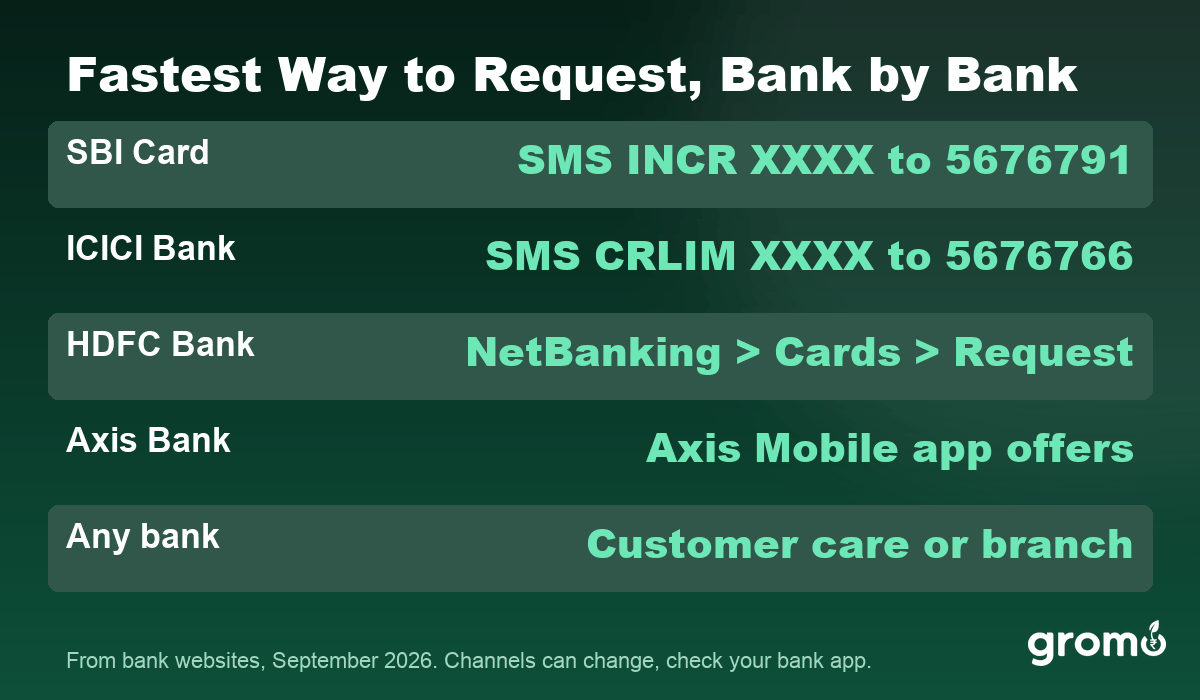
- SMS: send INCR followed by the last 4 digits of your card to 5676791 from your registered mobile number.
- App or website: log in and open the Benefits section.
- WhatsApp: type "Credit Limit Increase" to check eligibility.
- Chatbot ILA or the SBI Card helpline.
No offer showing? You can request an increase through the SBI Card app or website by sharing Account Aggregator consent for your main bank account, or by submitting income documents: the last 2 months of salary slips for salaried applicants, or the latest ITR plus 3 months of bank statements for the self-employed.
ICICI Bank
- SMS: send CRLIM followed by the last 4 digits of your card to 5676766. ICICI says the limit is raised to the maximum you are eligible for.
- iMobile app: Cards, select your card, Manage Card, then Manage Credit Limit.
- Internet banking: My Accounts, Credit Card, Manage Credit Limit.
- WhatsApp or customer care on 1800 1080.
ICICI's terms allow a limit review after 12 months of card membership, and eligibility depends on repayment history, income profile, and internal assessment.
HDFC Bank
In HDFC NetBanking, go to Cards, choose Credit Card, then Request and Credit Limit Enhancement. You can also view and accept eligible offers in the HDFC app or MyCards.
HDFC states there are no charges for increasing the limit, the facility is available only on primary cards, and enhancements are offered to select customers based on usage, repayment, and spending.
Axis Bank and other banks
Axis Bank and most other issuers show pre-approved limit increase offers inside their mobile app and net banking when you qualify. If none appears, call customer care or visit a branch with income proof. The same rule applies everywhere: your repayment record and income decide the outcome, not the channel you use.
Temporary limit increase for a big purchase
Need extra room for one purchase, like a wedding or medical bill? Some banks offer a temporary limit increase.
SBI Card, for example, offers select cardholders a temporary increase for a set period, confirmed by OTP, after which the limit returns to the original amount. Plan to pay the extra spend back before the temporary period ends to avoid charges.
Does increasing your limit affect your credit score?
Usually it helps. Your credit utilisation ratio, the share of your limit you use, is a major part of your score. If you spend Rs 20,000 a month on a Rs 40,000 limit, that is 50 percent utilisation. Raise the limit to Rs 80,000 with the same spending and it drops to 25 percent, which scores better.
Pre-approved offers are based on the bank's own data. A request backed by new income documents may involve a fresh credit check, so avoid applying to several banks at once.
The full picture of what moves your score is in how to improve your credit score, and this is also the practical answer to how to increase credit overall: use less of the limit you have, and pay on time.
Request rejected? What to do next
- Wait 6 months and keep following the four-step method before asking again.
- Check your credit report for missed payments or errors, and fix them first.
- Get a second card instead. Two cards add to your total available credit, but RBI rules mean issuers assess your total limits across all lenders, so apply only when your profile is strong. See credit card eligibility before you apply.
- Consider a secured card backed by a fixed deposit if your score is low. The limit is tied to the FD, and good use builds your history, covered in credit card for low CIBIL score.
Mistakes that keep your limit low
Asking too early. Requesting in the first few months, before any payment history exists, almost always fails.
Maxing out the card. High utilisation month after month tells the bank you are stretched, the opposite of what earns an increase.
Paying only the minimum. It avoids late fees but signals strain, and interest on the rest makes the card expensive, one of several credit card hidden charges worth knowing.
Help others get the right card, and earn
If you understand how limits and approvals work, you can help people choose cards they will actually get approved for. On GroMo, partners recommend credit cards from multiple banks and earn Rs 500 to 2,000 per approved card.
The catalogue lists 29 credit cards and 7 secured credit cards at the time of writing, useful for customers with low scores too. The approval side is explained in how credit card approval works.
Recommend the right credit card to the right person and earn commission on every approval. Free to join.
FAQ: how to increase credit card limit
1. How do I increase my credit card limit instantly?
Check your bank's app for a pre-approved offer. SBI Card and ICICI also let you check by SMS: INCR plus the last 4 card digits to 5676791 for SBI, CRLIM plus the last 4 digits to 5676766 for ICICI. Pre-approved increases are often approved instantly without documents.
2. How can I increase my credit card limit without documents?
Accept a pre-approved offer, which banks make based on your usage and repayment history. If none is showing, keep using the card responsibly for a few more months, since document-free offers come from good account behaviour.
3. How to raise credit card limit on SBI Card?
Send INCR and the last 4 digits of your card to 5676791, or check the Benefits section in the SBI Card app. Without a pre-approved offer, request through the app with Account Aggregator consent or income documents.
4. How to up your credit card limit at HDFC Bank?
Use HDFC NetBanking: Cards, Credit Card, Request, then Credit Limit Enhancement, or accept an offer in the app. HDFC charges nothing for this, and it is available only on primary cards.
5. How often can I request a credit limit increase?
Space requests at least 6 months apart. ICICI's terms allow a review after 12 months of membership, and repeated requests do not improve your chances.
6. Can a bank increase my limit without asking me?
No. RBI rules prohibit unilateral limit increases, and your explicit consent, usually by OTP, is required every time. Banks can lower your limit, but must inform you.
7. Does a higher credit limit improve my CIBIL score?
Usually yes, because it lowers your credit utilisation ratio when your spending stays the same. The benefit disappears if you spend more just because the limit is higher.
8. Why was my limit increase request rejected?
Common reasons are a short card history, late or minimum-only payments, high utilisation, low recorded income, or too much existing debt. Fix these for 6 months and request again.
Disclaimer
Processes, SMS codes, and eligibility rules are taken from the official websites of SBI Card, ICICI Bank, and HDFC Bank and the RBI Master Direction as of September 2026, and banks can change them without notice, confirm the current process in your bank's app before acting.
Limit increase decisions rest entirely with the card issuer. GroMo commissions are indicative, depend on approvals by partner banks, and can change. This article is for information only and is not financial advice. GroMo is available only to users aged 18 and above.


