
Loan App Without CIBIL: What's Real and What's a Trap
Loan app without CIBIL check: what these apps actually do, why no RBI-regulated lender skips the credit check entirely, and safer options if your score is low.
By Arvind Kumar · Published 12 October 2026 · Updated 12 October 2026
A loan app without CIBIL check, in the strict sense, does not exist among RBI-regulated lenders. Every regulated lender runs some credit assessment before disbursing. What genuinely exists are apps that lend to low scores rather than no score, apps that weigh bank statements and income more heavily than the bureau, and secured products where your own deposit removes the lender's risk. Anything advertising approval with no check at all is either unregulated or not telling you the whole truth.
Key takeaways- No RBI-regulated lender skips the credit check entirely (RBI digital lending framework, retrieved 2026-10-12). "Without CIBIL" means low score accepted, not no check. - Apps lending to thin or low files price that risk in, so the interest rate is higher. - A secured product backed by your own deposit is the honest route when the score is the obstacle. - Check the lender is RBI-registered before sharing a single document.
What does "loan app without CIBIL" actually mean?
Marketing shorthand covers three genuinely different things here.
Definition — CIBIL score. A credit score issued by TransUnion CIBIL, one of four credit bureaus licensed by the Reserve Bank of India (RBI, retrieved 2026-10-12). Lenders use it to judge repayment history.
Low score accepted. The lender still pulls your bureau report but sets its cut-off lower than a bank would. The score matters; the bar is just further down.
Alternative data weighted higher. Some NBFCs lean on bank statement inflows, salary credits and app-based behaviour rather than treating the bureau score as decisive. Common for people with a thin file rather than a bad one.
Secured against a deposit. A fixed deposit or similar backs the facility, so the lender's exposure is covered and the score matters far less.
Only the third genuinely reduces the role of your score. The first two still check it.
Why no regulated lender skips the check
Under RBI's digital lending framework, the regulated entity carries responsibility for the loan and for assessing whether you can repay it. Lending without any assessment is not a service, it's a liability the lender cannot accept.
When an app says "no CIBIL required", ask what it means. A reputable one means it accepts low scores. An unregulated one may mean it doesn't care whether you can repay, because its business model is recovery pressure rather than lending.
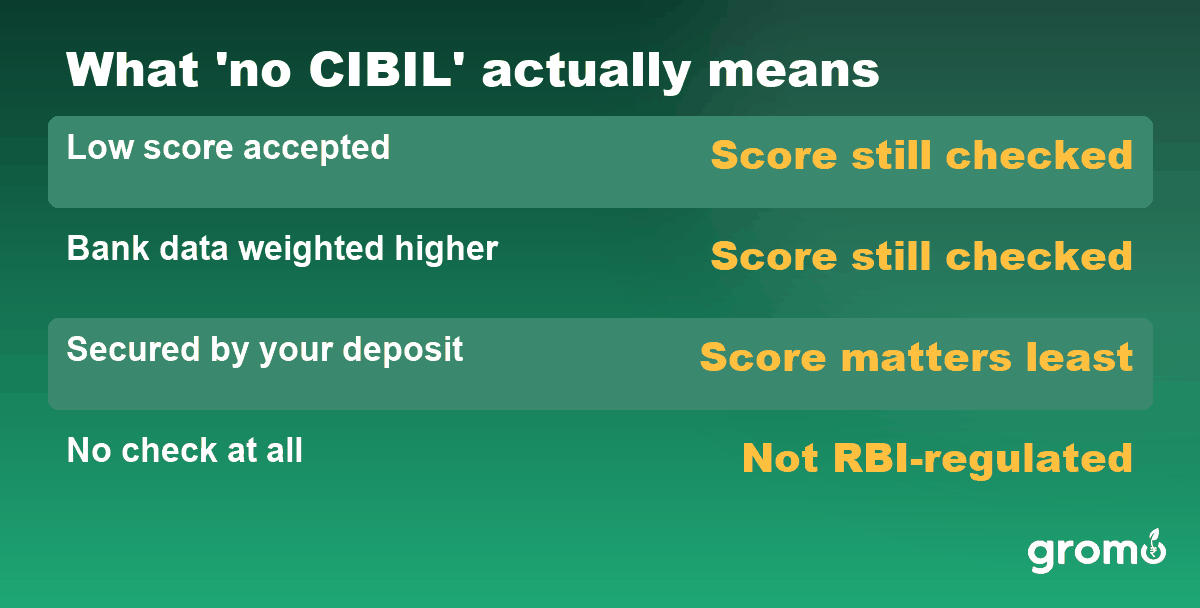
Three different products hide behind one phrase. Image: GroMo.
Warning signs of a predatory loan app
No named lender. Every legitimate app names the RBI-registered bank or NBFC actually lending the money. If you cannot find that name, stop.
A fee before disbursal. Processing fees are deducted from the disbursed amount. Being asked to pay anything upfront, by UPI, to receive a loan is the clearest fraud signal there is.
Very short tenures with large charges. A seven-day loan with heavy fees is a debt trap by design, however small the headline number looks.
Contacts and gallery permissions. An app demanding your full contact list has a recovery strategy, not a lending model.
Rates quoted only per day or per week. Converting to an annual rate usually reveals why they presented it that way.
Our list of fake loan apps documents these patterns in detail.
How to check a lender is genuine before applying
- Find the lender's name in the app, usually in the terms or the FAQ.
- Check it against RBI's registry of banks and NBFCs.
- Read the Key Fact Statement showing the APR, not just the interest rate.
- Confirm the APR, which includes processing fees and charges, rather than the headline rate.
- Check the grievance channel exists and names a real officer.
Any app failing step one fails all of them. There's no reason to proceed.
Better options when your score is the problem
A secured credit card. You place a fixed deposit and receive a card against it. The deposit removes the lender's risk, so approval depends far less on your score, and using the card responsibly rebuilds your credit history. GroMo lists 7 secured credit card products paying between ₹400 and ₹1,750 per approved case (GroMo product catalogue, retrieved 2026-10-12).
A smaller amount from a regulated NBFC. Many lenders approve a modest first loan on a thin file, then raise the limit once you've repaid.
Fix the score first where you can wait. Clearing an overdue account and keeping utilisation low moves a score faster than most people expect.
Borrow against an asset. A loan against a deposit or against mutual fund units is secured and far cheaper than unsecured credit at a low score.
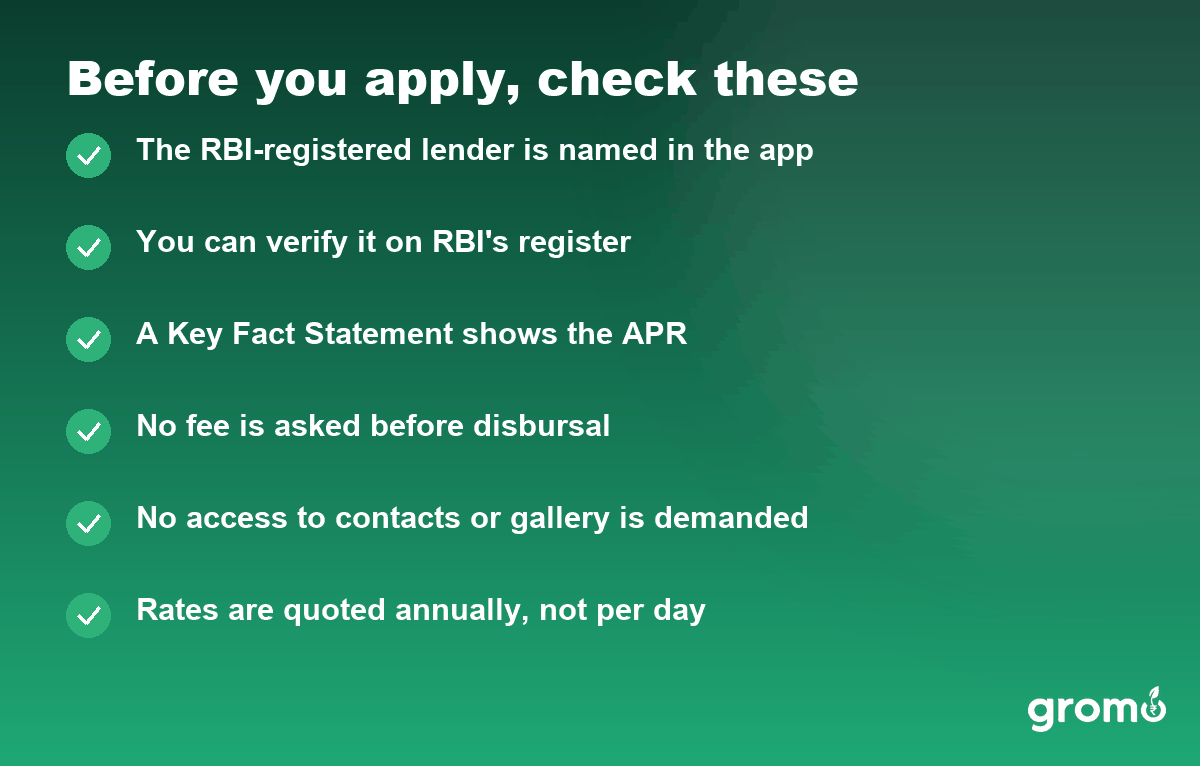
Any app failing the first check fails all of them. Image: GroMo.
What it costs to borrow at a low score
The honest answer is: more. A lender accepting more risk prices that risk in, and the gap between a prime rate and a subprime one is substantial.
Two consequences follow. The total repayable can be far above what the monthly figure suggests, so always check the APR rather than the EMI. And a short tenure with a high rate can cost more in absolute rupees than a longer tenure at the same rate, despite finishing sooner.
Borrowing at a low score is sometimes necessary. Doing it without reading the APR rarely is, and the RBI approved loan apps guide shows how to verify a lender first.
Referring loan products with GroMo
GroMo is an Indian financial-products distribution platform where individuals refer products from partner banks and NBFCs and earn a commission when a referral is approved.
Four relevant products pay between ₹325 and ₹1,750 per approved referral (GroMo product catalogue, retrieved 2026-10-12):
| Product | Commission per approved referral |
|---|---|
| HDFC Secured Credit Card | ₹1,750 |
| Lendingplate Personal Loan | ₹500 |
| IDFC WOW! BLACK Credit Card | ₹500 |
| InCred Personal Loan | ₹325 |
Rates are campaign-linked and change without notice. Commission is paid only on approved cases, and lenders decline a meaningful share of low-score applications, so referring someone to a product they cannot get helps nobody. The personal loan guide covers eligibility before you refer.
Frequently asked questions
Below are the questions people most often ask alongside this one.
Is there any loan app without CIBIL check?
Not among RBI-regulated lenders. Every regulated lender assesses creditworthiness. Apps advertising no check at all are either unregulated or mean they accept low scores rather than no score.
Which loan app approves a low CIBIL score?
Several NBFCs do lend to lower scores by weighting bank statements and income more heavily. Expect a higher interest rate, since the lender is pricing additional risk.
Can I get a loan with a 400 CIBIL score?
Getting one is difficult and expensive from unsecured lenders. A secured product backed by your own deposit is usually the realistic route, and it rebuilds the score for next time.
How do I check whether a loan app is genuine?
Find the RBI-registered lender named in the app, verify it against RBI's registry, and read the Key Fact Statement for the APR. An app that won't name its lender should not be used.
Do loan apps without CIBIL charge more?
Yes, generally. A lender accepting greater risk prices it into the rate, so compare the APR rather than the monthly instalment.
Is it safe to give a loan app access to my contacts?
No. An app requiring your contact list is building a recovery mechanism, not assessing your creditworthiness. Treat the request as a reason to uninstall.
What's the fastest way to improve a low CIBIL score?
Clear any overdue amount, keep credit utilisation low, and maintain a regular repayment record. A secured card used carefully is one of the more reliable rebuilding tools.
Summary
A loan app without CIBIL check doesn't exist among regulated lenders. The phrase describes apps that accept low scores, apps weighting bank data over the bureau, or secured products where your deposit carries the risk. Always find the RBI-registered lender's name, read the APR rather than the EMI, and treat any upfront fee or contacts permission as a reason to stop. If the score is the obstacle, a secured product is usually the honest route, and credit cards for a low CIBIL score covers those.
Disclosures
GroMo (Vitrak Technologies Pvt Ltd) is a distribution platform. GroMo is not a bank, NBFC, insurer or investment adviser. All products are offered by their respective RBI, IRDAI or SEBI-regulated providers.
Partner earnings depend on effort, product mix and customer eligibility. Any figures shown are illustrative examples of individual results. They are not typical and are not guaranteed. GroMo does not guarantee any level of income.
Loan approval, interest rate, APR and terms are at the sole discretion of the lender. Rates and eligibility criteria vary by lender and change without notice. This article is general information, not financial advice. Read the Key Fact Statement before applying for any credit product.
Written by Arvind Kumar. Published 12 October 2026. Last updated 12 October 2026.
Sources
- Reserve Bank of India, digital lending framework and the register of banks and NBFCs. Retrieved 12 October 2026. https://www.rbi.org.in/
- GroMo product catalogue, commission rates by product. Retrieved 12 October 2026.


