
Best 7 Days Loan Apps List 2026: Instant Approval Options
15 best 7 days loan apps list for 2026 — regulated instant short term loan options, the risks of illegal no-CIBIL apps, and how to stop loan app harassment.
People searching for a 7 days loan apps list usually need one thing: small cash, fast, for a very short time. This guide gives you that (and if you're new to digital credit, start with how to get an instant loan safely) — but with the honesty most lists skip. Short-term digital credit platforms like mPokket, Pocketly, KreditBee, Fibe, and CASHe genuinely offer fast, app-based small loans.
However, apps promising strict 7-day ultra-short loans are frequently unverified, operate outside Reserve Bank of India (RBI) guidelines, and are known for extreme harassment and high hidden fees. Legitimate lenders rarely run true 7-day lifespans — they offer flexible tenures starting from about 1 to 3 months with rapid same-day disbursal, which solves the same emergency without the trap.
Below you'll find the regulated short-term apps worth knowing, a Top 15 list of instant loan options from RBI-regulated banks and NBFCs, the specific risks of illegal 7-day apps — especially the "without CIBIL score" kind — and exactly what to do if a loan app harasses you.
Popular Regulated Short-Term Loan Apps
- mPokket: small-ticket loans starting from ₹500, built for students and young workers; short flexible tenures with quick app-based approval.
- Pocketly: micro-loans with quick digital processing, aimed at immediate small financial gaps.
- KreditBee: fast processing with customised short-to-long repayment cycles as your limit grows.
- Fibe (EarlySalary): quick salary advances and short-term loans for working professionals, disbursed rapidly.
- CASHe: rapid credit lines and short-term personal financing based on your income profile.
- Quikkred: app-based short-term personal loans with digital KYC; as with any newer lending app, verify its current RBI-registered lending partner inside the app before applying.
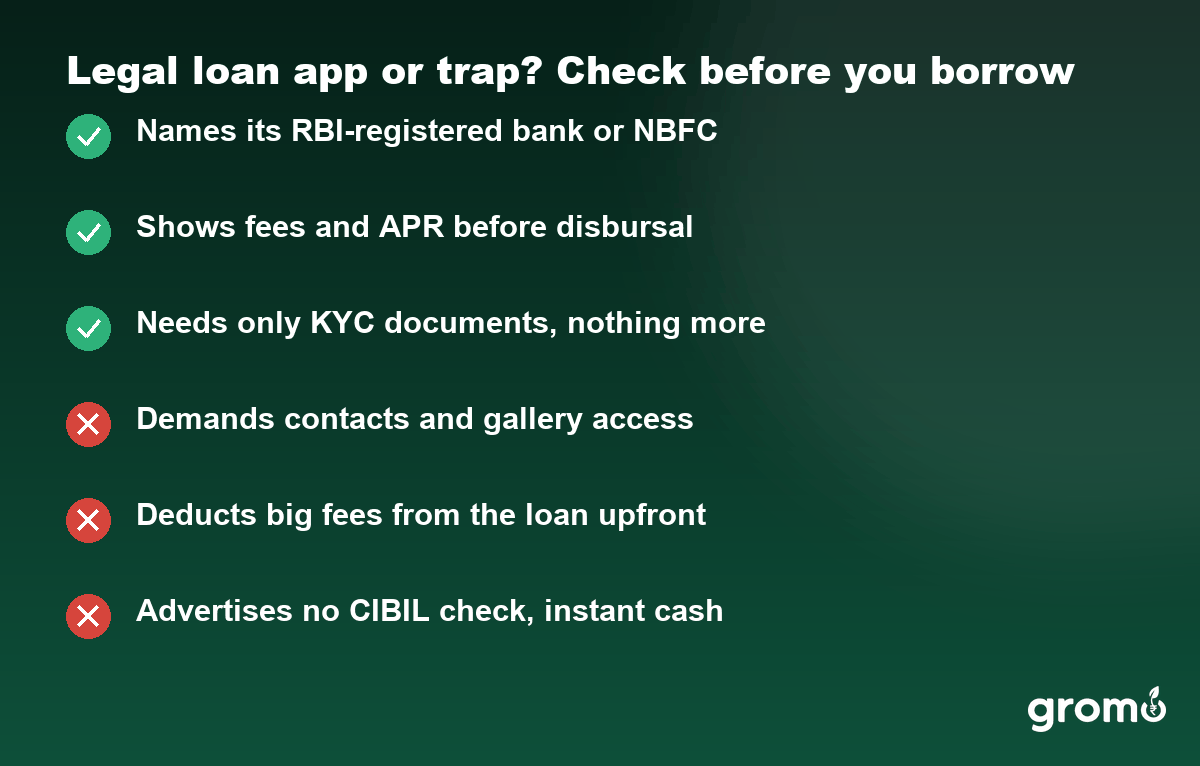
Common thread: all of these disclose their RBI-registered NBFC or bank lending partner, state fees in a Key Fact Statement before disbursal, and report to credit bureaus. That is what separates a short-term loan from a trap.
Top 15 Instant Short-Term Loan Options in India
These 15 options come from established banks and NBFC-backed lending platforms offering digital personal loans with fast approval and disbursal — the legitimate way to solve the same emergency a “7-day app” pretends to:
| App / Lender | Typical amount | Tenure | Approval speed | Credit check |
|---|---|---|---|---|
| Zype | Up to ~Rs 5 lakh | 6 to 24 months | Minutes | Soft check |
| Moneyview | Rs 10,000 to ~Rs 10 lakh | 3 months to 5 years | Same day | Standard |
| Kissht | Rs 10,000 to ~Rs 5 lakh | 3 to 60 months | Minutes to hours | Standard |
| Hero FinCorp | Up to ~Rs 5 lakh | 12 to 36 months | Same day | Standard |
| Ram Fincorp | Rs 5,000 to ~Rs 1 lakh | 3 to 12 months | Hours | Flexible |
| PayMe | Rs 5,000 to ~Rs 5 lakh | 3 to 24 months | Same day | Standard |
| Ring | Small ticket | Flexible, short | Minutes | Flexible |
| LendingPlate | Rs 10,000 to ~Rs 2.5 lakh | 3 to 12 months | Same day | Standard |
| FatakPay | Rs 1,000 to ~Rs 2 lakh | 3 to 12 months | Hours | Flexible |
| Tez Credit | Small ticket | 3 to 6 months | Hours | Flexible |
| Quikkred | Small ticket | Short tenure | Hours | Verify current terms |
| InCred | Rs 50,000 to ~Rs 10 lakh | 12 to 60 months | Same day | Standard |
| Poonawalla Fincorp | Rs 1 lakh to ~Rs 30 lakh | 12 to 60 months | Same day | Standard |
| IDFC FIRST Bank | Rs 20,000 to ~Rs 10 lakh | 6 to 60 months | Minutes for pre-approved | Standard |
| Bajaj Finserv | Rs 20,000 to ~Rs 25 lakh+ | 12 to 96 months | Minutes for eligible | Standard |
Figures are indicative ranges as of September 2026 and change with lender offers, always verify the live terms inside each app before applying.
- Zype Personal Loan — fully digital small-ticket loans with quick approval for salaried users.
- Moneyview Personal Loan — flexible amounts and tenures with a fast in-app process.
- Kissht Personal Loan — instant credit with short repayment cycles.
- Hero Instant Personal Loan — quick-disbursal personal financing from Hero FinCorp.
- Ram Fincorp Instant Personal Loan — small instant loans with digital KYC.
- PayMe Personal Loan — short-term salary-linked loans processed online.
- Ring Personal Loan — app-based credit for smaller, shorter needs.
- LendingPlate Personal Loan — quick short-tenure personal loans for salaried applicants.
- FatakPay Personal Loan — small-ticket digital credit with fast turnaround; lending is provided by FDPL Finance Private Limited (FFPL), an RBI-registered NBFC that disburses all loans on its own books.
- Tez Credit Personal Loan — instant small loans with minimal documentation.
- Quikkred — app-based short-term personal loans with digital KYC and quick processing; confirm its current lending entity in the RBI DLA directory before applying.
- InCred Personal Loan — established NBFC lending with quick digital approval.
- Poonawalla Fincorp Personal Loan — reputed NBFC with fast personal loan disbursal.
- IDFC FIRST Bank Personal Loan — bank-grade instant personal loans, fully digital.
- Bajaj Finserv Personal Loan — one of India's largest NBFCs with instant approval for eligible profiles.
Before applying with any of them, do the same check you would for any loan app: confirm the lending entity behind the platform in the RBI's Digital Lending Apps (DLA) directory and read the Key Fact Statement — regulated lenders state fees upfront and report to credit bureaus, meaning on-time repayment actually builds your CIBIL score instead of hiding from it. Availability, amounts, and tenures vary by your profile — check each lender's live offer before applying.
Which 7 Days Loan Apps Give Instant Approval?
Instant approval in the regulated world means an automated decision in minutes for pre-verified profiles, not money with zero checks. Among the options above, Zype, Kissht, Bajaj Finserv, and IDFC FIRST Bank routinely approve eligible salaried applicants within minutes, and disburse the same day once KYC is complete. If an app promises instant approval with no KYC and no income question, that speed is the scam, not the service.
Need 7 to 15 Days Only? Your Real Options
If you genuinely need money for one or two weeks, you do not need a risky 7-day app. Take the smallest amount a regulated lender offers on a 3-month tenure and prepay in the first fortnight, most NBFC apps in the table allow early repayment with little or no foreclosure charge on small loans. The interest cost of holding a Rs 10,000 regulated loan for 15 days is a few hundred rupees, a fraction of what illegal 7-day and 15-day apps extract through processing-fee deductions.
Why "7 Days Loan App List Without CIBIL Score" Is the Riskiest Search
Adding "without CIBIL score" to the search multiplies the danger, and it's worth understanding why:
- Legitimate lenders must assess repayment ability. RBI-regulated banks and NBFCs check credit history or income because it's responsible lending. An app that advertises "no CIBIL check, instant cash" is announcing that it doesn't follow the rules regulated lenders live by.
- The business model is the fee, not the loan. No-CIBIL 7-day apps profit from processing fees deducted upfront (₹1,000 borrowed, ₹700 received), daily penal charges, and forced rollovers — effective annualised rates can run into thousands of percent.
- Your data becomes the collateral. Since they skip credit checks, these apps demand your contacts and gallery instead — repayment is enforced through shame, not law.
- It doesn't build your future. These apps don't report to bureaus, so even perfect repayment leaves your CIBIL exactly where it was. A secured credit card or a small regulated loan builds your credit score; a rogue app never will.
If your score is low or absent, the safe paths are: a smaller loan amount from a regulated lender, a secured credit card against a fixed deposit, or a guarantor, not an unregulated app.
That said, a low or missing score does not lock you out of regulated credit entirely. Several RBI-compliant platforms use alternative data, income, bank transactions, and repayment behaviour, alongside or instead of a hard CIBIL cut-off:
- mPokket: small loans from Rs 500 aimed at students and young earners, light documentation.
- KreditBee: entry-level limits for new-to-credit users that grow with repayment history.
- CASHe: uses its own social-and-income based scoring for salaried applicants.
- Fibe: salary-linked credit with soft checks on smaller first loans.
These are soft-check options, not no-check options. Every one of them still verifies identity and income, which is precisely what separates them from the fake apps.
7 Days Loan App APK Download: Never Install It
A large share of searches in this space end in “apk”, looking for a 7 days loan app APK file from a website or a forwarded link. Do not do this under any circumstances. APK files sideloaded from outside the Play Store skip every security review, and they are exactly how fake 7-day loan apps get onto phones, harvesting contacts, photos, and OTPs the moment permissions are granted.
There is no legitimate loan app that exists only as an APK. Every RBI-compliant lender in this article distributes through the official Play Store and App Store. If an app is not there, or a site urges you to download its “latest version APK”, treat it as a scam and close the page.
Risks of Illegal 7-Day Loan Apps
- High interest rates and charges: processing fees can take up a massive chunk of the small principal disbursed, and daily penalties compound brutally on a 7-day clock.
- Data privacy abuse: unregulated 7-day apps often demand access to your phone contacts, gallery, and personal data — which they use for public shaming, morphed photos, and harassment calls to your family if repayment is delayed by even a day.
- No RBI oversight: shady apps on short 7-day cycles usually lack backing from legitimate Non-Banking Financial Companies. Always verify the app names an RBI-registered lender — see our RBI approved loan apps list — the RBI and app stores have removed thousands of such apps, but new ones appear weekly — our fake loan apps list tracks known offenders.
Safety Guidelines Before Taking Any Instant Cash Loan Online
- Verify the lender, not the app. Find the RBI-registered bank/NBFC the app lends on behalf of, then cross-check it in the RBI's official Digital Lending Apps (DLA) directory — live on the RBI website since 1 July 2025 precisely so customers can verify a loan app's claimed association with a regulated entity. Not in the directory and no named lender = uninstall.
- Read the Key Fact Statement. RBI's digital lending rules require fees, APR, and tenure disclosed before disbursal. If money arrives before terms are shown, that's a violation and a warning.
- Refuse contact/gallery permissions. A legitimate loan app needs KYC documents — never your phonebook or photos.
- Never pay to receive a loan. "Advance fees," "GST unlock charges," and "insurance to release funds" are pure fraud patterns.
- Download only from official app stores, never from APK links in WhatsApp, Telegram, or SMS.
- Borrow the amount you can repay from the next inflow — and prefer a 1–3 month tenure over a 7-day cliff; the EMI difference is small and the safety difference is enormous.
Facing Loan App Harassment? Do This
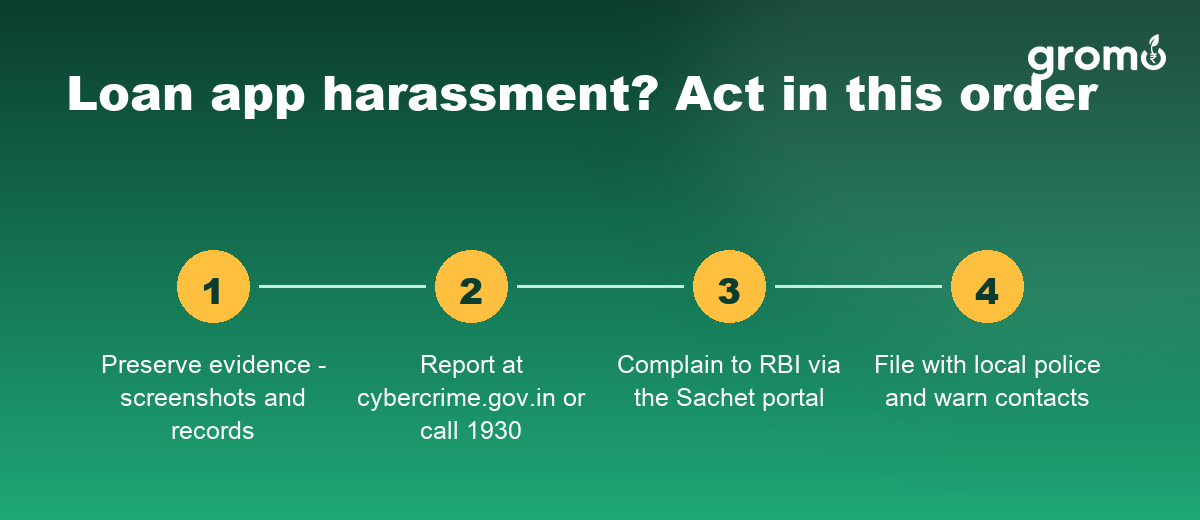
The Government of India and RBI treat recovery harassment by illegal loan apps seriously, and the protections are now concrete: the RBI (Digital Lending) Directions, 2025 (issued 8 May 2025) make fair recovery conduct, data privacy, and grievance redressal mandatory for regulated lenders, their service providers, and their apps; MeitY has blocked 87 illegal loan apps under Section 69A of the IT Act; and the Indian Cyber Crime Coordination Centre (I4C) proactively analyses digital lending apps (source: PIB, Ministry of Finance, July 2026). If you are being harassed, act in this order:
- Stop engaging and preserve evidence: screenshots of threats, call recordings, the app name, and transaction records.
- Report to the National Cyber Crime Portal: file at cybercrime.gov.in or call the helpline 1930 immediately — harassment, morphed images, and threats are prosecutable offences.
- Complain to RBI: use the SACHET portal (sachet.rbi.org.in) — the public platform for complaints against entities collecting money illegally — and the RBI Ombudsman (cms.rbi.org.in) if a registered lender's recovery agents misbehave.
- Inform your local police / cyber cell — an FIR strengthens every other complaint.
- Warn your contacts that a scam app may call them, defusing the shaming tactic these operators rely on.
- Do not pay extortion demands beyond legitimate dues — payments to harassers fund more harassment.
The Bottom Line: Choose Regulated Over "7 Days"
The real answer to the 7-day loan search is not a riskier app — it is faster access to regulated credit. The Top 15 above are established digital lending options with digital KYC and tenures that give you room to repay without a cliff — verify each one's regulated lending entity in the RBI DLA directory before applying. Verify the lender, read the Key Fact Statement, borrow only what your next inflow can cover, and report any harassment through the channels above. If you find it easier to compare several of these lenders in one place, many of the loan products listed are also available through the GroMo app.
FAQ: 7 Days Loan Apps
Is the 7 days loan app legal in India?
Genuine RBI-regulated lenders almost never offer strict 7-day loans — their short-term products start around 1-3 months. Apps built specifically on 7-day cycles typically operate without an RBI-registered lending partner, which makes them illegal lenders. Before borrowing from any app, verify the bank or NBFC named in it against the RBI's registers; if no lender is named, do not borrow.
Which app gives an instant cash loan online safely?
Regulated options include mPokket, KreditBee, Fibe, CASHe, Pocketly, and the 15 established lending options in this guide — such as Zype, Moneyview, Kissht, IDFC FIRST Bank, and Bajaj Finserv. All disclose fees before disbursal, need only KYC documents, and disburse digitally, often the same day for eligible profiles. Check each lender's live offer, amount range, and tenure in its app before applying.
Where can I get an urgent cash loan?
For an urgent cash loan, go straight to an RBI-regulated lender: mPokket, KreditBee, or Fibe for small amounts, or the larger banks and NBFCs covered in the personal loan apps list. Regulated apps disburse within a few hours to a day after KYC. If you have no salary slips, some regulated lenders still work, see the options for personal loans without income proof. Avoid any app that promises money in minutes with zero verification, that speed usually signals an illegal lender.
Can I get a 7 days loan app with instant approval and no CIBIL score?
Apps advertising instant approval with no CIBIL check are the highest-risk category in digital lending — no regulated lender skips credit assessment entirely. They substitute your contacts and photos as collateral and recover through harassment. If your score is low, safer routes are a smaller amount from a regulated lender, a secured credit card against a fixed deposit, or building score for 3-6 months first.
What should I do if a loan app is harassing me or my contacts?
Preserve evidence (screenshots, recordings), report immediately at cybercrime.gov.in or helpline 1930, complain to RBI via the Sachet portal, and file with your local police or cyber cell. Recovery harassment, threats, and misuse of your photos are criminal offences. Warn your contacts that a scam app may call them — removing the shame removes the app's leverage.
Which is better: a 7-day loan or a 1-3 month short-term loan?
A 1-3 month tenure from a regulated lender is almost always safer and barely costs more. Seven-day cycles exist mainly in unregulated apps because they maximise rollover fees and default pressure. A regulated short-term loan spreads repayment across pay cycles, discloses its full cost upfront, and reports your good repayment to credit bureaus — improving your future borrowing instead of endangering it.
Is FatakPay RBI-registered?
FatakPay is a digital financial platform, and lending on it is provided by FDPL Finance Private Limited (FFPL), an RBI-registered Non-Banking Financial Company (NBFC). All loans offered through FatakPay are disbursed directly by FFPL on its own books, in compliance with applicable RBI regulations. This is exactly the structure to look for in any loan app — a named, verifiable RBI-regulated lender behind the platform.
Which 7 days loan app has instant approval?
No regulated lender guarantees instant approval, but pre-checked profiles on Zype, Kissht, Bajaj Finserv, and IDFC FIRST Bank often see decisions in minutes, with disbursal the same day. Instant approval promises combined with no verification at all are a scam marker, not a feature.
Is there a 7 days loan app APK I can download?
Do not install loan app APKs from websites, Telegram, or WhatsApp forwards. Sideloaded APKs bypass Play Store security checks and are the main delivery route for fake 7-day loan apps that steal contacts and photos. Install lending apps only from the official Play Store or App Store.
How can I get Rs 1,000 urgently?
The fastest regulated route for Rs 1,000 is a student and young-earner app like mPokket, which lends from Rs 500 with basic KYC, or a small limit on KreditBee. Approval takes minutes to hours and money reaches your bank the same day. Avoid any app or Telegram contact offering Rs 1,000 in seconds, that speed always hides a fee scam.
How can I get Rs 2,000 immediately?
Apply on a small-ticket regulated app like mPokket, KreditBee, or FatakPay with your PAN and Aadhaar ready. First-time limits of Rs 1,000 to 5,000 are common, and disbursal after KYC usually lands within hours. Immediately means the same day with a real lender, never the same minute.
How can I get an instant Rs 2,000 loan?
The same small-ticket apps, mPokket, KreditBee, CASHe, handle Rs 2,000 instantly in the regulated sense: automated approval in minutes for eligible profiles, money in your account within hours of completing KYC. An app that skips KYC entirely for instant money is a scam, not a shortcut.
How can I get a Rs 3,000 loan fast?
Rs 3,000 sits comfortably inside first-loan limits on KreditBee, mPokket, Fibe, and CASHe. Keep PAN, Aadhaar, and a bank statement or salary proof ready, apply in the app, and a decision typically comes the same day. Prepay early if the tenure is longer than you need, small-loan foreclosure charges are usually nil or tiny.
How can I get Rs 3,000 rupees immediately?
Same answer as fast: a regulated small-ticket app with your documents ready is the immediate option that exists. If the timeline is truly hours, borrow from family or your employer's salary-advance option first, both cost nothing, and use the loan app as the fallback.
How can I get Rs 5,000 immediately?
Rs 5,000 is within the starting range of KreditBee, Fibe, CASHe, and Zype for salaried users, and mPokket for students. Complete KYC properly the first time, mistakes are the main cause of delayed disbursal. Same-day arrival is realistic, same-minute promises are the scam signature.
How can I get a Rs 10,000 loan on my Aadhaar card?
Aadhaar alone is not collateral, it is your KYC document. Every regulated app pairs it with PAN and an income check, and that combination gets a Rs 10,000 loan approved digitally on apps like KreditBee, Moneyview, Kissht, or Fibe, often the same day. Any site offering Aadhaar-only loans with no PAN and no income question is harvesting your identity.
Can I get an urgent Rs 10,000 loan without a CIBIL score?
Yes, through the soft-check platforms listed above, mPokket, KreditBee, CASHe, and Fibe use income and bank-transaction data alongside or instead of a hard CIBIL cut-off. Expect a smaller first limit, sometimes below Rs 10,000, that grows after on-time repayments. No score is workable, no verification at all is a scam.
Can I get a loan in 5 minutes?
Approval in 5 minutes is real for pre-verified profiles on apps like Zype, Kissht, and Bajaj Finserv. Money in your bank in 5 minutes is not, even the fastest regulated disbursals take from around 30 minutes to a few hours after KYC. Treat any promise of cash in minutes with zero checks as an illegal lender.
Disclaimer
This article is general information, not financial or legal advice, and nothing here is an offer of credit. The Top 15 list reflects lender offerings at the time of writing; lender availability, loan amounts, tenures, interest rates, fees, and eligibility are decided entirely by each RBI-regulated bank or NBFC and change without notice — always check the live offer, Key Fact Statement, and terms in the lender's own app before applying. Some of the products listed are also available via the GroMo app; GroMo is a distribution platform, not a lender, and does not approve, disburse, or guarantee any loan.
Third-party app names (mPokket, Pocketly, KreditBee, Fibe, CASHe, Quikkred, and others) are trademarks of their respective owners; inclusion is informational and not an endorsement. Borrow only what you can repay, and never pay any upfront fee to receive a loan.


